

Is a 10-Year Home Loan Right for You?
10 year home loan rates currently average 5.83% (APR 5.93%) as of June 2026 — lower than both 15-year and 30-year fixed mortgage rates. Here’s a quick snapshot to answer the most common question right away:
| Loan Term | Average Rate | Average APR |
|---|---|---|
| 10-Year Fixed | 5.83% | 5.93% |
| 15-Year Fixed | 5.92% | 6.03% |
| 20-Year Fixed | 6.35% | 6.47% |
| 30-Year Fixed | 6.55% | 6.63% |
Rates as of June 11, 2026. Source: national averages.
So yes — a 10-year mortgage offers the lowest rate of all major fixed terms. But the lower rate comes with a significantly higher monthly payment.
That trade-off is exactly what this guide is about.
A 10-year mortgage lets you own your home outright in a decade. You pay far less interest over the life of the loan. But your monthly payment will be roughly double what you’d pay on a 30-year loan for the same amount.
It’s a powerful move — if your budget can handle it.
Whether you’re buying your first home or refinancing to finally get debt-free, understanding how these rates work can save you tens of thousands of dollars.
Understanding 10 Year Home Loan Rates Today

When we look at the mortgage landscape in June 2026, the cost of borrowing has settled into a new normal. If you have been tracking the markets, you know that rates have experienced their fair share of volatility over the last few years. However, the shorter amortization schedule of a 10-year loan keeps it consistently positioned as the most affordable fixed-rate option on the market.
To put this in perspective, the average interest rate for a 10-year fixed mortgage sits at 5.83% (5.93% APR). This is a noticeable step down from the 15-year fixed rate of 5.92% and a massive discount compared to the 30-year fixed average of 6.55%. If you want to explore how these rates fit into your home purchasing or refinancing goals, you can Explore 10-Year Mortgage Options to see what is available for your specific scenario.
But why does this rate difference exist, and how does it play out in your everyday budget? Let’s break down the mechanics.
How 10 Year Home Loan Rates Compare to 15-Year and 30-Year Terms
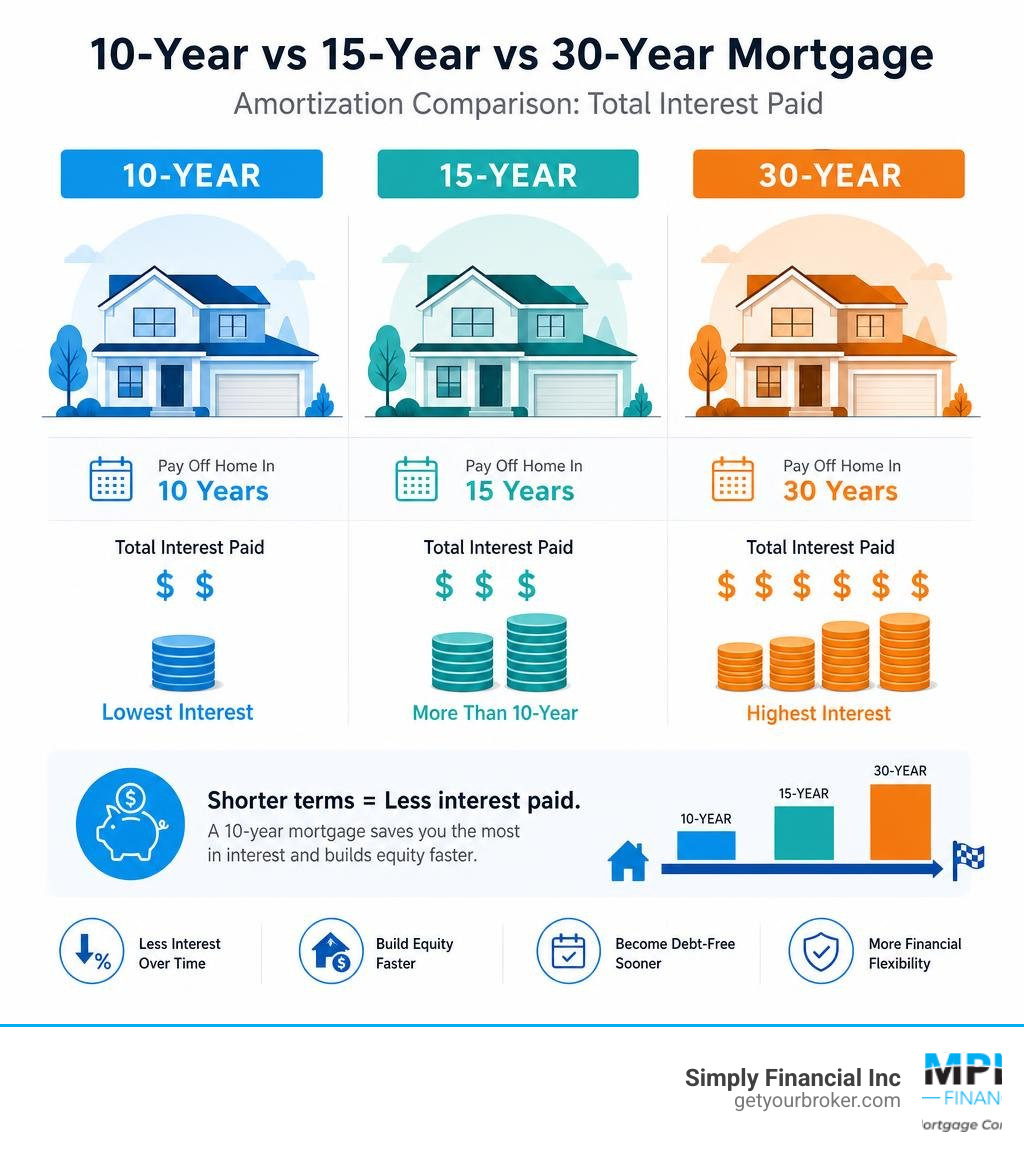
The primary reason borrowers gravitate toward shorter-term mortgages is the sheer volume of interest savings. Because you are paying off the principal balance in 10 years instead of 30, the lender has less time to charge you interest, and the rate itself is lower because the lender takes on less long-term inflation risk.
Let’s look at a real-world comparison. Imagine you are looking to secure a $250,000 mortgage. Here is how the numbers stack up across different terms based on current June 2026 rates:
| Mortgage Term | Interest Rate | Monthly Principal & Interest | Total Interest Paid Over Loan Life |
|---|---|---|---|
| 10-Year Fixed | 5.83% | $2,754 | $80,480 |
| 15-Year Fixed | 5.92% | $2,100 | $128,000 |
| 30-Year Fixed | 6.55% | $1,588 | $321,680 |
Look at those numbers for a second. By choosing a 10-year term over a 30-year term:
- You save a staggering $241,200 in total interest.
- You pay off your home 20 years sooner.
- You build equity at a lightning-fast pace from day one.
However, the catch is glaringly obvious: your monthly payment on the 10-year loan is $1,166 higher than the 30-year option. That is why this loan is not for everyone. It requires a strong, stable income and a comfortable cushion in your monthly cash flow. If you want to dive deeper into how these options compare, you can use online mortgage calculators or consult with a mortgage professional to run the numbers for your specific situation.
Why Shorter-Term Rates Differ Across Lenders
Not all lenders price 10-year mortgages the same way. In fact, because 10-year mortgages are considered a “niche” product—representing only about 1% to 2% of all mortgage originations—many major banks do not actively advertise them.
Because of this, you will often find the most competitive 10 year home loan rates at credit unions and regional portfolio lenders rather than major national banks. Portfolio lenders are financial institutions that keep the mortgages they originate on their own books rather than selling them to government-sponsored enterprises like Fannie Mae or Freddie Mac. Because they hold the risk, they have more flexibility to offer lower rates to borrowers with pristine credit profiles.
Highly competitive credit unions, for example, have recently offered 10-year rates as low as 5.25% to 5.75% for members with top-tier credit scores and large down payments. Lenders use risk-based pricing, meaning the less risk you present to them, the lower the rate they will offer you.
How 10-Year Mortgage Rates Are Determined
Mortgage rates do not just appear out of thin air. They are shaped by a complex mix of macroeconomic forces and your personal financial health.
On a grand scale, mortgage rates are heavily influenced by the bond market—specifically 10-year Treasury yields—and the market for Mortgage-Backed Securities (MBS). When investor demand for safe-haven assets like Treasury bonds increases, yields drop, and mortgage rates generally follow. Conversely, when inflation fears rise, investors demand higher yields, which pushes mortgage rates up.
While the Federal Reserve does not directly set mortgage rates, its monetary policy decisions dictate the broader interest rate environment. When the Fed raises or lowers its benchmark federal funds rate to combat inflation or stimulate the economy, it sends a ripple effect through the entire financial sector. For the latest updates on how these national trends impact local markets, keeping an eye on financial news and market reports can provide excellent context.
Personal Financial Factors That Impact Your Rate
While Wall Street and the Federal Reserve set the baseline, your financial profile determines the final rate a lender will offer you. Here are the key ingredients lenders look at when cooking up your personalized rate quote:
- Credit Score: This is the heavyweight champion of rate determination. A score of 740 or higher secures the absolute best rates. If your score is in the mid-600s, you will likely pay a higher rate to offset the lender’s risk.
- Debt-to-Income (DTI) Ratio: Lenders want to make sure your monthly debt obligations (including your new mortgage payment) do not consume too much of your pre-tax income. For a 10-year mortgage, which naturally carries a high payment, having a low DTI is crucial.
- Loan-to-Value (LTV) Ratio and Down Payment: Putting down 20% or more reduces your LTV to 80% or lower. This eliminates the need for Private Mortgage Insurance (PMI) and signals to the lender that you have skin in the game, which lowers your rate.
Pros and Cons of a 10-Year Fixed Mortgage
Choosing a mortgage term is all about balancing your current lifestyle with your future financial goals. Here is a transparent look at the advantages and disadvantages of committing to a 10-year fixed mortgage.
The Pros:
- Unmatched Interest Savings: You pay a fraction of the interest compared to a 30-year term.
- Rapid Wealth Building: Because your early payments go heavily toward the principal balance rather than interest, you build home equity at an incredibly fast rate.
- True Financial Freedom: You will own your home free and clear in just 10 years, eliminating your largest monthly expense right as you might be entering retirement or sending kids to college.
The Cons:
- High Monthly Commitment: The payments are steep. If you experience a job loss or financial emergency, you are locked into that high payment.
- Opportunity Cost: Money tied up in home equity cannot be easily accessed. You might earn a higher return by taking a 30-year loan and investing your extra cash in the stock market or other investments.
- Reduced Purchasing Power: Because the monthly payments are so high, you may qualify for a much smaller loan amount, forcing you to buy a less expensive home.
Is a 10-Year Mortgage Right for You?
We find that 10-year mortgages are highly popular among specific groups of homeowners:
- Refinancers: If you are 10 to 15 years into a 30-year mortgage, refinancing into a 10-year loan lets you secure a lower rate and keep your original payoff timeline without resetting the clock.
- Downsizers: Empty nesters who sell a large family home and buy a smaller property often use their existing equity to take out a small 10-year mortgage, ensuring they are entirely debt-free in retirement.
- Peak Earners: Individuals in their highest-earning years who want to aggressively eliminate debt before their income drops or they transition to new career phases.
If you are trying to decide which path aligns with your long-term goals, we can help you compare More info about mortgage loan options to find the perfect fit.
How to Qualify for the Best 10 Year Home Loan Rates
Qualifying for a 10-year mortgage is more rigorous than qualifying for a standard 30-year loan. Because the monthly payments are significantly higher, lenders will scrutinize your income stability and debt profile with extra care.
To secure the absolute lowest 10 year home loan rates, aim to meet these gold-standard qualifications:
- A Credit Score of 740+: While you can qualify with a lower score, the premier rates are reserved for excellent credit.
- A Healthy Down Payment: Having a down payment of 20% or more keeps your loan-to-value ratio low and helps you avoid PMI.
- A Low DTI Ratio: Keep your total debt-to-income ratio under 43% (and ideally under 36%) to prove you can comfortably absorb the higher monthly payment.
Ready to see where you stand? You can easily start the process and get pre-approved by completing our Pre-Qualify Chicago Mortgage Pre-Approval form.
Frequently Asked Questions about 10-Year Mortgages
Navigating the mortgage market can raise a lot of questions. Here are the answers to some of the most common inquiries we receive from borrowers exploring 10-year loan terms.
Should I lock in my 10-year mortgage rate today?
Locking in your rate is generally a smart move if you are under contract and plan to close within the next 30 to 45 days. Because mortgage markets are highly sensitive to daily economic news and inflation reports, rates can fluctuate. A rate lock protects you from unexpected upward swings while your loan is being processed. If you believe rates might drop before you close, ask your mortgage consultant about a “float-down” option, which allows you to capture a lower rate if the market improves.
Can I get a 10-year mortgage with a lower credit score?
Yes, you can. While conventional guidelines typically require a minimum credit score of 620, government-backed options like FHA loans can allow for lower credit scores. Additionally, some portfolio lenders are willing to look at your broader financial picture—such as substantial cash reserves or a very low DTI—to approve a 10-year loan even if your credit score is not perfect.
How do 10-year rates vary by location?
Mortgage rates can vary slightly depending on where you are buying. Local property tax rates, regional foreclosure laws, and the level of competition among local lenders all play a role in how loans are priced.
For example, if you are shopping for a home in the Midwest, you can research local market trends and average rates in Illinois. If you are looking to purchase in the Sunshine State, you can explore regional rate averages for Florida.
To explore customized local programs tailored to your area, take a look at our specific Illinois mortgage options.
Conclusion
At Simply Financial Inc, we believe that choosing a mortgage is not just about finding a place to live—it is about designing a secure financial future. A 10-year home loan is one of the most aggressive and rewarding wealth-building tools available to homeowners. By securing a lower interest rate and committing to a shorter payoff timeline, you can save a small fortune in interest and enjoy the unmatched peace of mind that comes with owning your home free and clear.
Whether you are looking to purchase a new home or refinance your existing mortgage, our team is here to provide a seamless, expert-guided, and stress-free mortgage experience. If you are located in Illinois or Florida, stop by our Chicago office at 5632 W Lawrence Ave Chicago IL, or connect with us online.
Ready to make your next big financial move? Discover More info about fixed rate mortgage Chicago options and let us help you find the perfect loan for your goals.