

The Truth About Buying a Home With Zero Down in 2026
If you’re exploring 100 financing home loans first time buyer options, here’s the short answer: yes, they exist, they’re legitimate, and several strong programs can get you into a home with absolutely no down payment.
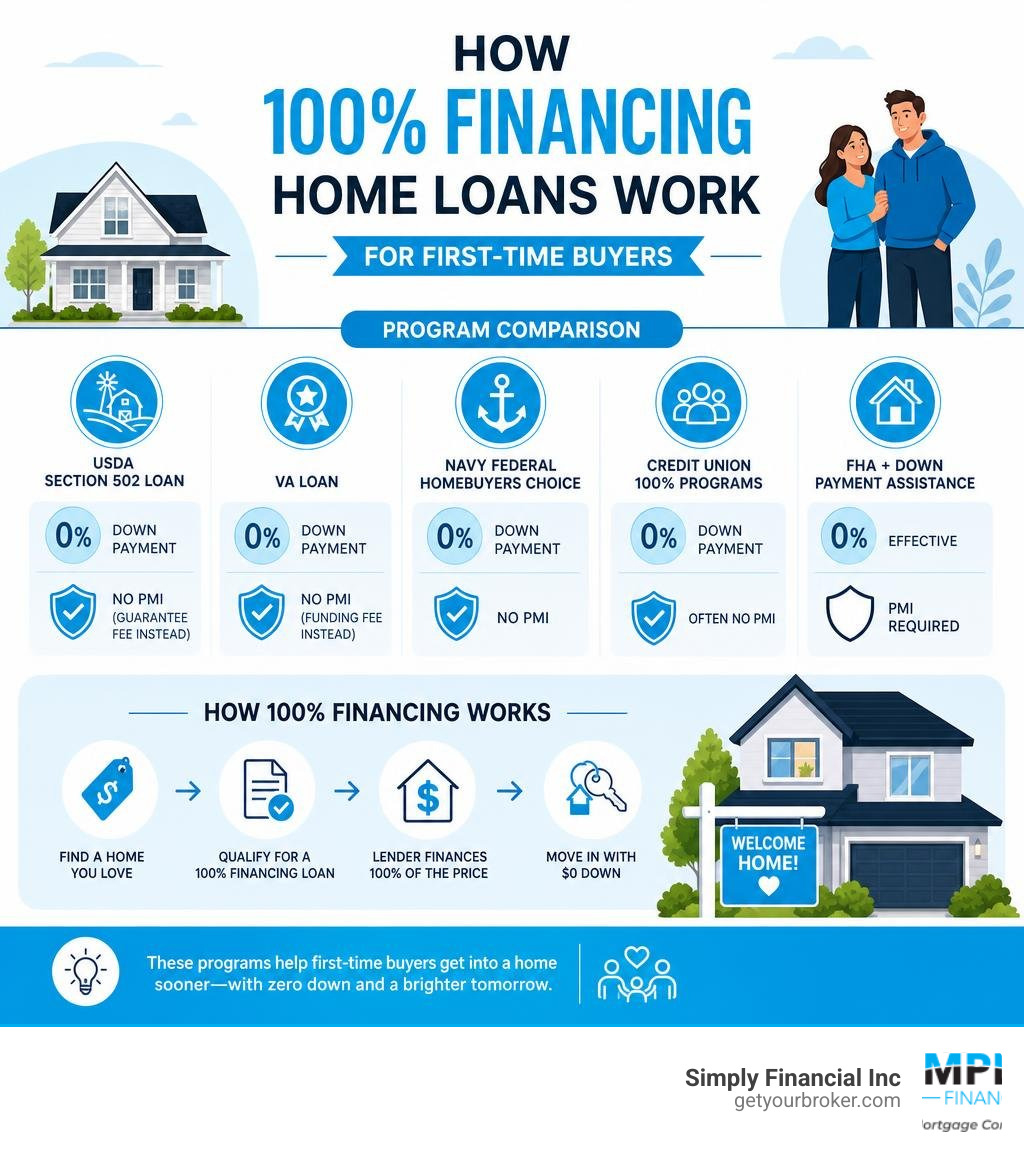
Quick answer — the main zero-down loan options available in 2026:
| Program | Who It’s For | Down Payment | PMI Required? |
|---|---|---|---|
| USDA Section 502 Loan | Rural area buyers, income limits apply | 0% | No (guarantee fee instead) |
| VA Loan | Veterans, active military, eligible spouses | 0% | No (funding fee instead) |
| Navy Federal Homebuyers Choice | Navy Federal members | 0% | No |
| Credit Union 100% Programs | Varies by lender and state | 0% | Often no |
| FHA + Down Payment Assistance | Most buyers, credit score 620+ | 0% effective | Yes |
For most first-time buyers, the hardest part of buying a home isn’t the monthly payment. It’s the down payment. Saving up 10% or 20% of a home’s purchase price can take years — sometimes a decade or more, especially in today’s market.
That’s exactly why 100% financing programs exist.
These loans let you borrow the full purchase price of a home, so you don’t need tens of thousands of dollars saved before you can even start shopping. Some programs also eliminate private mortgage insurance (PMI), which can save you hundreds of dollars every month.
The catch? These programs do come with eligibility rules — things like income limits, geographic restrictions, credit score minimums, and property type requirements. Knowing which program fits your situation is the key to making this work.
This guide breaks it all down in plain language, so you can stop wondering and start moving forward.
Understanding 100 financing home loans first time buyer Options
When we talk about a 100% financing home loan, we mean a mortgage where the loan-to-value (LTV) ratio is exactly 100%. In simple terms, if the home costs $350,000, the lender writes a check for $350,000. Your down payment is a clean, round $0.
While this sounds like magic, it is actually a highly structured financial tool. Traditional mortgages require you to put skin in the game because it reduces the lender’s risk. If you have no equity in the home on day one, the lender takes on all the risk if you default. To offset this, 100% financing programs are backed by either government guarantees (like the USDA or VA) or strict underwriting guidelines from private institutions and credit unions.
For first-time buyers, the primary benefit is clear: you bypass the years of renting while watching home prices outpace your savings. However, starting with 0% equity means your initial monthly payments will be higher than if you had put money down, and building equity will take a bit longer.
It is also important to note that these programs are almost exclusively reserved for a primary residence. You cannot use a 100% financing mortgage to buy a vacation condo in Destin or a rental property in Chicago. Lenders want to know you are living in the home because owner-occupied properties have significantly lower default rates.
If you are on the fence about whether zero down is right for you, it is highly useful to compare these programs against a Low Down Payment Mortgage Chicago to see which pathway fits your monthly budget and long-term financial goals.
Government-Backed No-Down-Payment Mortgages
The most popular and secure ways to achieve 100% financing are through federal government programs. Because the federal government guarantees a portion of these loans, lenders are willing to offer excellent interest rates with no down payment whatsoever.

USDA Loans: 100 financing home loans first time buyer in Rural Areas
The USDA Section 502 Guaranteed Loan Program is one of the housing market’s best-kept secrets. While many assume “rural” means buying a working farm in the middle of nowhere, the USDA’s definition of rural is surprisingly generous. Many quiet suburbs, outer-ring communities, and small towns in both Illinois and Florida qualify.
To be eligible for a USDA loan, you must meet a few key criteria:
- Geographic Boundaries: The home must be located in a USDA-eligible designated area.
- Income Limits: Because this program is designed to help low-to-moderate-income households, your household income cannot exceed 115% of the local median income.
- Loan Terms: These are strictly structured as 30-year fixed-rate mortgages, ensuring your monthly payments remain stable and predictable.
The USDA program does not have a strict minimum credit score set by the government, though most lenders look for a score of 620 or higher for streamlined processing. Instead of traditional private mortgage insurance (PMI), the USDA charges an upfront guarantee fee and an annual fee that is built into your monthly payment, which is typically much cheaper than conventional PMI.
VA Loans: 100 financing home loans first time buyer for Military Families
If you have served in the U.S. military, are currently on active duty, or are an eligible surviving spouse, the VA home loan is hands-down the best mortgage product on earth.
Backed by the Department of Veterans Affairs, VA loans offer 100% financing with zero down payment and absolutely no monthly mortgage insurance. This lack of monthly PMI saves military families hundreds of dollars every single month compared to conventional or FHA loans.
To get started, you will need a Certificate of Eligibility (COE), which proves your service history meets the minimum requirements (typically 90 days of active service during wartime or 181 days during peacetime).
While there is no monthly PMI, the VA program does charge a one-time “VA Funding Fee” at closing. This fee helps keep the program running for future generations of veterans. The fee is a percentage of the loan amount and varies based on whether it is your first time using the benefit, but the best part is that the funding fee can be rolled directly into your loan balance so you still pay $0 out of pocket on closing day.
Down Payment Assistance (DPA) and Specialized Programs
What if you aren’t in the military and you want to buy a home in the heart of Chicago or a bustling Florida metro area where USDA loans don’t apply? You can still achieve a true 100% financing structure by pairing an FHA loan or conventional loan with Down Payment Assistance (DPA) programs.

This is often structured as a “silent second” lien. For example, a program might provide a 96.5% LTV FHA first mortgage paired with a 3.5% DPA second mortgage. Together, they cover 100% of the purchase price. Many of these second liens are structured as forgivable loans—meaning if you stay in the home for a certain number of years (usually 5 to 10), the second loan is completely erased, leaving you with free equity!
Most DPA programs require you to complete a basic, HUD-approved homebuyer counseling course. These quick courses are incredibly helpful, teaching you the basics of maintaining a home, budgeting for property taxes, and managing your mortgage.
State and Local DPA Programs
Depending on where you live, there are excellent local resources designed to bridge the down payment gap for first-time buyers.
Illinois and Chicago Programs
If you are buying in the Land of Lincoln, the Illinois Housing Development Authority (IHDA) is your go-to resource. Learning about Getting An IHDA Loan is a fantastic first step, as they regularly offer thousands of dollars in forgivable down payment assistance. Furthermore, state-level support is highly active; for instance, Gov. Pritzker Launches Down Payment Assistance Program for First … programs frequently introduce new grants to make home buying accessible.
If you are looking specifically within the city limits, check out the resources provided For Homebuyers – City of Chicago and explore the specialized grants offered via the Down Payment Assistance | Chicago Housing Authority . You can also view our comprehensive breakdown of local grants on our First Time Home Buyer Programs Chicago page.
Florida Programs
For our Florida buyers, the state offers robust options like the Florida Housing Finance Corporation’s Hometown Star program and local credit union partnerships. You can read a detailed roadmap on How to Get a No Down Payment Home Loan in Florida to see how regional programs can help you purchase a home with zero down.
Additionally, military members and general buyers can look into national programs with regional footprints, such as those detailed in No Down Payment Mortgage Loans | Navy Federal Credit Union , or explore localized credit union options like Your First Mortgage – U of I Community Credit Union for regional programs in college town areas. Major national lenders also offer specialized first-time products, which you can compare by checking out First-time Homebuyer Loans and Programs | Wells Fargo .
Comparing 100% Financing to Low Down Payment Options
Is 100% financing always the best route? Not necessarily. Sometimes putting just 3% or 3.5% down can secure you a lower interest rate or cheaper monthly mortgage insurance. Let’s look at how these options stack up side-by-side.
Program Comparison Table
| Feature | 100% Financing (USDA/VA) | FHA Loan (with 3.5% Down) | Conventional 97% (with 3% Down) |
|---|---|---|---|
| Down Payment | 0% | 3.5% | 3% |
| PMI Type | None (VA) / Low Annual Fee (USDA) | Monthly & Upfront MIP (Lifetime of loan) | Private PMI (Cancellable at 80% LTV) |
| Credit Score Min | Typically 620 | 580 (or 500 with 10% down) | Typically 620 – 640 |
| Property Rules | Strict (Rural for USDA / VA standards) | Flexible (Any standard home) | Flexible (Any standard home) |
| Interest Rates | Generally very competitive | Competitive, but MIP adds to cost | Based heavily on credit score |
Choosing the right path depends on your liquid savings. If you have $15,000 saved, using it for a 3% down payment on a conventional loan might get you a slightly lower interest rate and allow you to drop your PMI once you reach 20% equity. However, if using that $15,000 leaves your bank account completely empty, you are far better off choosing a 100% financing option and keeping that cash in reserve for unexpected home repairs or moving costs.
Pros, Cons, and Application Steps for First-Time Buyers
Before jumping into a zero-down mortgage, it is wise to weigh both sides of the coin.
The Pros:
- Instant Homeownership: You don’t have to spend the next five years paying a landlord while saving for a massive down payment.
- Keep Cash Reserves: You can keep your savings intact for moving costs, new furniture, or emergency repairs.
- Competitive Rates: Government-backed programs like VA and USDA loans often have lower interest rates than conventional loans.
The Cons:
- Higher Monthly Payments: Financing 100% of the home means your principal loan amount is higher, leading to larger monthly payments.
- Slower Equity Growth: Because you start with $0 in equity, it will take longer to build enough home equity to refinance or sell and walk away with a significant check.
- Stricter Eligibility: You must meet specific geographic, income, or military service requirements.
Steps to Prepare and Apply
If you are ready to take the plunge, here is how to position yourself for a smooth, stress-free approval:
- Optimize Your Credit: Before applying, check your credit report. If you have limited credit history, learn How to Establish First Time Credit to boost your score.
- Gather Your Documents: Lenders will want to see your last two years of tax returns, W-2s, recent pay stubs, and bank statements.
- Ask for Seller Concessions: While your down payment is $0, you still have closing costs (usually 2% to 4% of the loan amount). You can ask the seller to pay these closing costs (up to 3% on conventional or 6% on FHA/USDA) to truly minimize your out-of-pocket expenses.
- Get Pre-Approved: Do not go house hunting without a pre-approval letter in hand. It shows sellers you are a serious, qualified buyer. You can easily start the process using our Pre-Qualify Form or read more about how the process works at Pre-Qualify Chicago Mortgage Pre-Approval.
Frequently Asked Questions About 100% Financing
Do I need a high credit score for a 100% financing home loan?
Not necessarily. While some private credit union 100% programs require a credit score of 720 or higher, government-backed options are much more flexible. VA loans have no official minimum credit score (though most lenders prefer a 580–620), and USDA loans typically require a 620 score for automated approval. If your score is lower, we can often perform manual underwriting to look at your overall financial picture.
Are there property type restrictions on zero-down loans?
Yes. These loans are strictly for primary residences—no second homes or investment properties allowed. Additionally, the home must meet basic safety and habitability standards. While single-family homes are the easiest to finance, townhomes and warrantable condos are also eligible. USDA loans have strict geographic boundaries, but no set acreage limits as long as the property is residential in nature.
What closing costs should I expect with a 100% financing loan?
Even with a $0 down payment, you will have closing costs. These include lender fees, appraisal fees, title insurance, and prepaids (setting up your escrow account for property taxes and homeowners insurance). Typically, closing costs run between 2% and 4% of the purchase price. However, these can often be covered via seller concessions, lender credits, or gift funds from family members.
Conclusion
Navigating 100 financing home loans first time buyer programs doesn’t have to be overwhelming. At Simply Financial Inc, our mission is to deliver a seamless, expert-guided, and stress-free mortgage experience. Whether you are looking to buy a home in Chicago, the surrounding Illinois suburbs, or anywhere in the state of Florida, we are here to help you find the perfect loan program.
Ready to explore your options and see how much home you can afford with zero down? Head over to our First Time Home Buyer Programs Chicago page to connect with our team and take your first step toward homeownership today!