

What Are Current Mortgage Rates for FHA Loans Right Now?
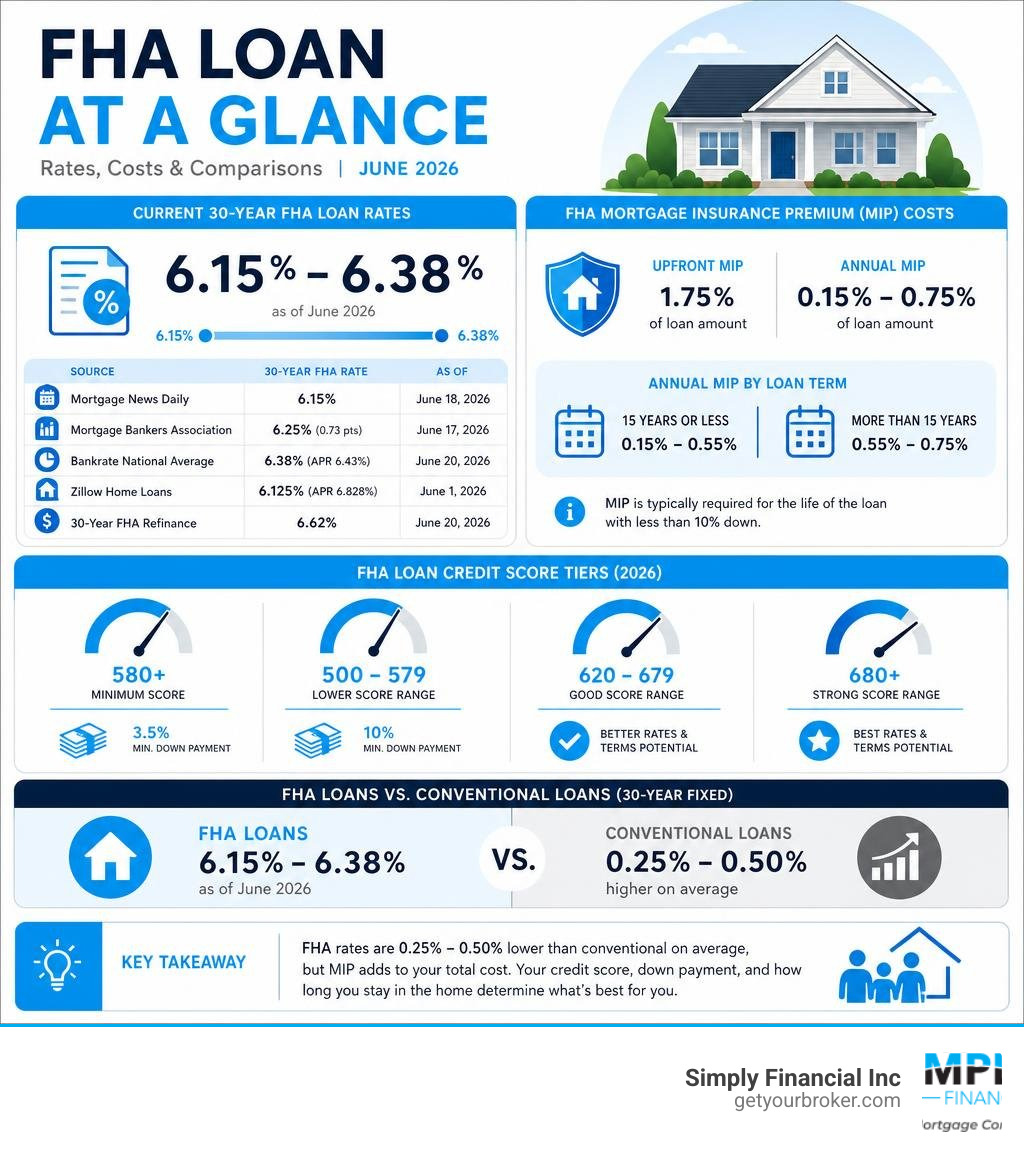
Current mortgage rates for FHA loans are sitting in the 6.15%–6.38% range for a 30-year fixed term as of June 2026, depending on the source and your lender.
Here’s a quick snapshot of where rates stand right now:
| Source | 30-Year FHA Rate | As Of |
|---|---|---|
| Mortgage News Daily | 6.15% | June 18, 2026 |
| Mortgage Bankers Association | 6.25% (0.73 pts) | June 17, 2026 |
| Bankrate National Average | 6.38% (APR 6.43%) | June 20, 2026 |
| National Lender Average | 6.125% (APR 6.828%) | June 1, 2026 |
| 30-Year FHA Refinance | 6.62% | June 20, 2026 |
These rates are 0.25%–0.50% lower than comparable conventional loan rates — but the total cost picture is more complicated once you factor in mortgage insurance.
That quick table is helpful, but the rate alone doesn’t tell the whole story. FHA loans come with required mortgage insurance premiums (MIP) that add to your monthly payment — sometimes for the entire life of the loan.
Your credit score, down payment, and how long you plan to stay in the home all change whether an FHA loan is actually the cheaper choice.
If you’re a first-time buyer, have a lower credit score, or don’t have a big down payment saved up, FHA loans can be a powerful option. But they’re not automatically the best deal for everyone — even when the rate looks lower.
This guide breaks it all down so you can make a confident, clear-eyed decision.
Understanding the Current Mortgage Rates for FHA Loans in June 2026
When you begin tracking current mortgage rates for FHA loans, you will quickly notice that daily headlines rarely match the exact rate quote you receive from a lender. In mid-June 2026, major industry trackers show a slight variation in national averages. The Mortgage News Daily daily survey pegged the average 30-year FHA rate at 6.15%, while the Mortgage Bankers Association weekly survey showed an average of 6.25% with 0.73 discount points.
These numbers do not come out of thin air. Instead, they are heavily influenced by the performance of Mortgage-Backed Securities (MBS). When investor demand for MBS is strong, yields drop, which translates into lower mortgage rates for home buyers. While the Federal Reserve’s federal funds rate decisions primarily dictate short-term debt, long-term mortgage rates react to the Fed’s economic outlook, inflation data, and broader bond market trends.
You can monitor these broader economic shifts through resources like Federal Reserve Economic Data (FRED). Because FHA loans are backed by the federal government through the HUD FHA Loan Program Details portal, lenders take on significantly less risk. This government backing is the primary reason why FHA interest rates are consistently lower than conventional interest rates.
How FHA Rates Compare to Conventional, VA, and Jumbo Loans
To understand where FHA loans sit in the broader market, it helps to compare them side-by-side with other common mortgage types. As of June 2026, here is how the national averages stack up:
| Loan Type | Average Interest Rate | Average APR | Key Advantage |
|---|---|---|---|
| 30-Year FHA | 6.15% – 6.38% | 6.43% – 6.82% | Low down payment, lenient credit guidelines |
| 30-Year Conventional | 6.53% – 6.82% | 6.59% | PMI can be removed at 20% equity |
| 30-Year VA | 5.78% – 6.54% | 6.58% | $0 down payment for eligible veterans |
| 30-Year Jumbo | 6.57% | 6.61% | High loan amounts for luxury properties |
While FHA interest rates look highly competitive next to conventional rates, the Annual Percentage Rate (APR) tells a different story. The FHA APR is notably higher because it factors in the mandatory upfront and annual mortgage insurance premiums. VA loans, which are also government-backed, generally boast the lowest interest rates on the market, but they are strictly reserved for eligible service members and veterans. Jumbo loans carry higher rates and much stricter underwriting guidelines because they are not backed by government agencies.
If you are looking at local options in the Midwest or the Southeast, you can compare these national baselines to state-specific indexes using resources like the Illinois mortgage and refinance rates for June 2026 – Bankrate page.
How Credit Scores and Down Payments Impact FHA Rates
One of the most common myths in real estate is that mortgage rates are “one-size-fits-all.” In reality, your personal financial profile is the ultimate deciding factor in what rate you are offered.

Lenders use credit score bands to determine your risk level. Even though the FHA allows for much lower credit scores than conventional programs, your score still influences the interest rate and the down payment you will be required to bring to the closing table.
- 720+ Credit Score: Borrowers in this tier receive the absolute lowest interest rates available and face minimal lender overlays.
- 620–679 Credit Score: This is the sweet spot for many FHA borrowers. While you might pay a slightly higher interest rate than a borrower with a 740 score, the rate will still be significantly lower than what you would get on a conventional loan with the same score.
- 580–619 Credit Score: You still qualify for the minimum 3.5% down payment, but lenders may charge higher origination fees or slightly adjust your interest rate upward.
- 500–579 Credit Score: You can still qualify for an FHA loan, but you must put down at least 10%.
Finding the Sweet Spot for Your Credit Score and Down Payment
For buyers working with a tighter budget, finding the right balance between credit score and down payment is essential. If your credit score is 580 or higher, you can take advantage of the standard FHA down payment of just 3.5%. If your score falls between 500 and 579, you must be prepared to make a 10% down payment.
If you are buying a home in the Chicagoland area, utilizing a Low Down Payment Mortgage Chicago program can help you bridge the gap. We specialize in structuring these loans to ensure you don’t have to drain your savings account just to get through the front door of your new home.
The Real Cost of FHA Loans: Upfront and Annual MIP
To truly understand current mortgage rates for FHA loans, you must look past the interest rate and analyze the Mortgage Insurance Premium (MIP). Unlike conventional loans, where private mortgage insurance (PMI) can be avoided by putting 20% down, FHA loans require mortgage insurance regardless of your down payment size.

There are two distinct parts to FHA mortgage insurance:
- Upfront Mortgage Insurance Premium (UFMIP): This is a one-time fee equal to 1.75% of your base loan amount. For example, on a $400,000 loan, your UFMIP would be $7,000. This amount is typically rolled into the total loan balance, meaning you pay interest on it over the life of the loan.
- Annual Mortgage Insurance Premium (MIP): Despite its name, this fee is divided by 12 and paid monthly as part of your regular mortgage payment. In March 2023, the FHA reduced this rate from 0.85% to 0.55% for most standard 30-year loans with a 3.5% down payment. On a $400,000 loan, this adds roughly $183 per month to your payment.
The duration of your annual MIP depends entirely on your initial down payment:
- Less than 10% down (e.g., 3.5% down): The annual MIP remains on the loan for the entire 30-year term. The only way to get rid of it is to refinance into a conventional loan once you reach 20% equity.
- 10% or more down: The annual MIP will automatically cancel after 11 years.
To see how these insurance costs affect your state-specific scenario, you can compare local rate offerings or speak with a licensed mortgage professional to run a personalized scenario.
FHA vs. Conventional: Total Cost Comparison Over Time
Because FHA loans require permanent mortgage insurance when you put down less than 10%, choosing between FHA and conventional financing requires a long-term mathematical comparison.
We always advise our clients to look at different holding periods—5, 10, and 30 years—before deciding on a loan program. You can explore all of these pathways in detail on our Mortgage Loan Options page.
Let’s look at a realistic scenario: a buyer purchasing a $400,000 home with a 3.5% down payment ($14,000 down) on an FHA loan versus a 3% down payment on a conventional loan.
- At Year 5: The FHA loan is often cheaper. Because FHA interest rates are typically 0.25% to 0.50% lower than conventional interest rates, the lower monthly interest payments offset the cost of the MIP during the first few years.
- At Year 10: The break-even point usually occurs here. By year 10, a conventional borrower’s home value has likely grown, allowing them to cancel their private mortgage insurance (PMI) once they reach 80% loan-to-value (LTV). Meanwhile, the FHA borrower is still paying $183+ per month in MIP.
- At Year 30: Over the full life of the loan, the conventional mortgage is almost always the more affordable option. The FHA borrower will have paid tens of thousands of dollars in non-cancellable mortgage insurance.
Analyzing Total Costs with Current Mortgage Rates for FHA Loans
When evaluating current mortgage rates for FHA loans, a lower interest rate does not automatically equal a lower total cost. If you have a credit score of 720 or higher, choosing an FHA loan purely because the headline interest rate is lower is often a financial mistake.
Conventional PMI rates are highly sensitive to credit scores. If your credit is excellent, your conventional PMI will be incredibly cheap—often much lower than the FHA’s flat 0.55% annual MIP. Furthermore, that conventional PMI will automatically disappear once you build 20% equity, whereas the FHA MIP will linger forever unless you refinance. You can cross-reference national rate sheets and run these calculations yourself using Compare current FHA loan rates – Bankrate.
FHA Loan Limits and Qualification Requirements for 2026
For 2026, the Federal Housing Administration has updated its loan limits to keep pace with shifting home prices. These limits act as a cap on the maximum amount you can borrow using an FHA mortgage, and they vary significantly by county.
- The FHA Floor (Standard Areas): For most low-to-moderate cost counties, the single-family home FHA loan limit is set at $541,288.
- The FHA Ceiling (High-Cost Areas): In expensive markets (such as high-cost coastal areas or select resort communities), the ceiling goes up to $1,249,125.
In the Chicago metropolitan area (including Cook County), the limits sit comfortably within the standard-to-moderate range, making FHA loans highly accessible for local properties. If you are a first-time buyer in the area, we highly recommend checking out our guide on First Time Home Buyer Programs Chicago to see how county limits and local grants can be combined.
Beyond loan limits, FHA qualification guidelines are famously accommodating:
- Debt-to-Income (DTI) Ratio: While conventional loans prefer a DTI under 43%, FHA loans can accept DTIs up to 50% (and occasionally up to 56.99% with strong compensating factors like excellent cash reserves).
- Employment History: You generally need a steady two-year employment history, but exceptions can be made for recent graduates or those returning to the workforce.
- Property Requirements: The home must serve as your primary residence and pass an FHA appraisal, which ensures the property meets basic safety, security, and structural soundness standards.
Pros and Cons of FHA Loans vs. Other Mortgage Options
To help you decide if an FHA loan aligns with your long-term financial goals, let’s look at the direct pros and cons compared to conventional, VA, and USDA loans.
The Pros:
- Lenient Credit Requirements: You can qualify with a credit score as low as 500 (with 10% down) or 580 (with 3.5% down).
- Lower Rates on Paper: Headline interest rates are typically lower than conventional rates.
- Assumable Mortgage: FHA loans are fully assumable. If you sell your home in a high-rate environment, a qualified buyer can “take over” your low FHA rate—a massive selling point.
- Flexible Co-Borrowers: FHA allows non-occupant co-signers (like parents) to help you qualify using their income.
The Cons:
- Permanent Mortgage Insurance: If you put down less than 10%, you pay MIP for the life of the loan.
- Strict Appraisal Standards: FHA appraisers look closely at minor issues like peeling paint or handrails, which sellers must repair before closing.
- Primary Residences Only: You cannot use an FHA loan to buy an investment property or a second home.
- Upfront Fees: The 1.75% UFMIP immediately increases your starting loan balance.
If you want to cast a wider net, you can compare these terms with national averages or consult with a mortgage broker to shop multiple lenders on your behalf.
Comparing Purchase vs. Refinance Current Mortgage Rates for FHA Loans
It is important to note that current mortgage rates for FHA loans differ depending on whether you are purchasing a home or refinancing an existing mortgage. FHA refinance rates are typically 0.25% to 0.50% higher than purchase rates. For example, in June 2026, while a purchase FHA rate might hover around 6.15%, an FHA refinance rate averages closer to 6.62%.
However, if you already have an FHA loan, you can take advantage of the FHA Streamline Refinance. This unique program allows you to lower your interest rate with:
- No new home appraisal.
- Minimal credit checks.
- No verification of income or employment.
This makes refinancing incredibly fast and stress-free when market rates drop. To lock in a favorable rate, you must work closely with your broker to monitor daily rate movements, as once you sign a rate lock, your interest rate is protected from market volatility for 15 to 60 days. You can read the official guidelines on the HUD FHA Requirements page.
Frequently Asked Questions About FHA Mortgage Rates
How often do FHA mortgage rates change?
FHA mortgage rates change daily, and sometimes multiple times a day. They fluctuate based on real-time trading of Mortgage-Backed Securities (MBS), inflation reports, employment data, and federal monetary policy.
Can FHA mortgage insurance be removed?
If you made a down payment of less than 10%, FHA mortgage insurance cannot be removed. The only way to eliminate it is to refinance your FHA loan into a conventional loan once you have reached at least 20% equity in your home. If you put down 10% or more at purchase, the MIP will automatically drop off after 11 years.
Can I use gift funds for my FHA down payment?
Yes! FHA guidelines are highly flexible when it comes to down payments. You can use gift funds from a family member, employer, or close friend to cover 100% of your down payment and closing costs. You will simply need a signed gift letter from the donor and documented proof of the wire transfer.
Conclusion
At Simply Financial Inc, we believe that buying a home should be an exciting milestone, not a source of financial stress. We are committed to delivering a seamless, expert-guided, and stress-free mortgage experience for buyers throughout Illinois and Florida.
Whether you are looking to purchase a historic bungalow in Chicago or a sun-drenched home in Florida, our physical team at 5632 W Lawrence Ave Chicago IL is ready to help you navigate the mortgage market.
Ready to see what rates you qualify for? Read more about our specialized programs on our FHA Loan Chicago page, and let us build a customized, cost-effective mortgage plan just for you!