

What First-Time Investors Need to Know About the FHA 203k Loan for Multifamily Properties
An fha 203k loan multifamily program is one of the most powerful — and most misunderstood — tools in real estate today. It lets you buy a 2-4 unit property that needs work and finance both the purchase and the renovations in a single mortgage, with as little as 3.5% down.
Here’s the short answer for anyone trying to decide if this loan is right for them:
FHA 203k Multifamily Loan — Quick Facts
| Feature | Details |
|---|---|
| Property types | 2-4 unit properties (duplex, triplex, fourplex) |
| Owner-occupancy required? | Yes — you must live in one unit |
| Minimum down payment | 3.5% (with 580+ credit score) |
| Loan versions | Limited (up to $75,000 in repairs) or Standard (major renovations) |
| Can rental income help you qualify? | Yes — up to 75% of market rent from other units counts |
| 5+ unit buildings eligible? | No — those require commercial FHA programs |
Most people searching for this topic want to know one thing: can I buy a duplex or triplex that needs work, live in one unit, rent out the others, and use one affordable loan to do it all?
The answer is yes — and that’s exactly what this guide covers.
The FHA 203k program has been around for decades, but it remains underused. Many buyers don’t realize it applies to 2-4 unit properties, not just single-family homes. And many first-time investors don’t know that rental income from the other units can actually help them qualify — sometimes dramatically lowering their effective debt-to-income ratio.
There’s also a common source of confusion worth clearing up early: when people say “FHA multifamily loan,” they’re often thinking of two very different programs. Properties with 1-4 units fall under standard residential FHA lending. Properties with 5 or more units require a completely different commercial program. This guide focuses on the residential side — the 203k loan for 2-4 unit properties.
Understanding the FHA 203k Loan Multifamily Program
When you set out to buy a multi-unit property in markets like Chicago, Illinois, or throughout Florida, you quickly realize that many of the most affordably priced duplexes, triplexes, and fourplexes are “fixer-uppers.” They might have outdated electrical systems, aging roofs, or kitchens that look like they were preserved from the 1970s.
Under standard mortgage guidelines, a property in this condition can be a dealbreaker. If you apply for a standard FHA Loan, the appraiser will flag these condition issues, and the lender will require them to be fixed before closing. This creates a classic catch-22: the seller won’t pay for the repairs, and you can’t get the loan to buy the property until the repairs are done.

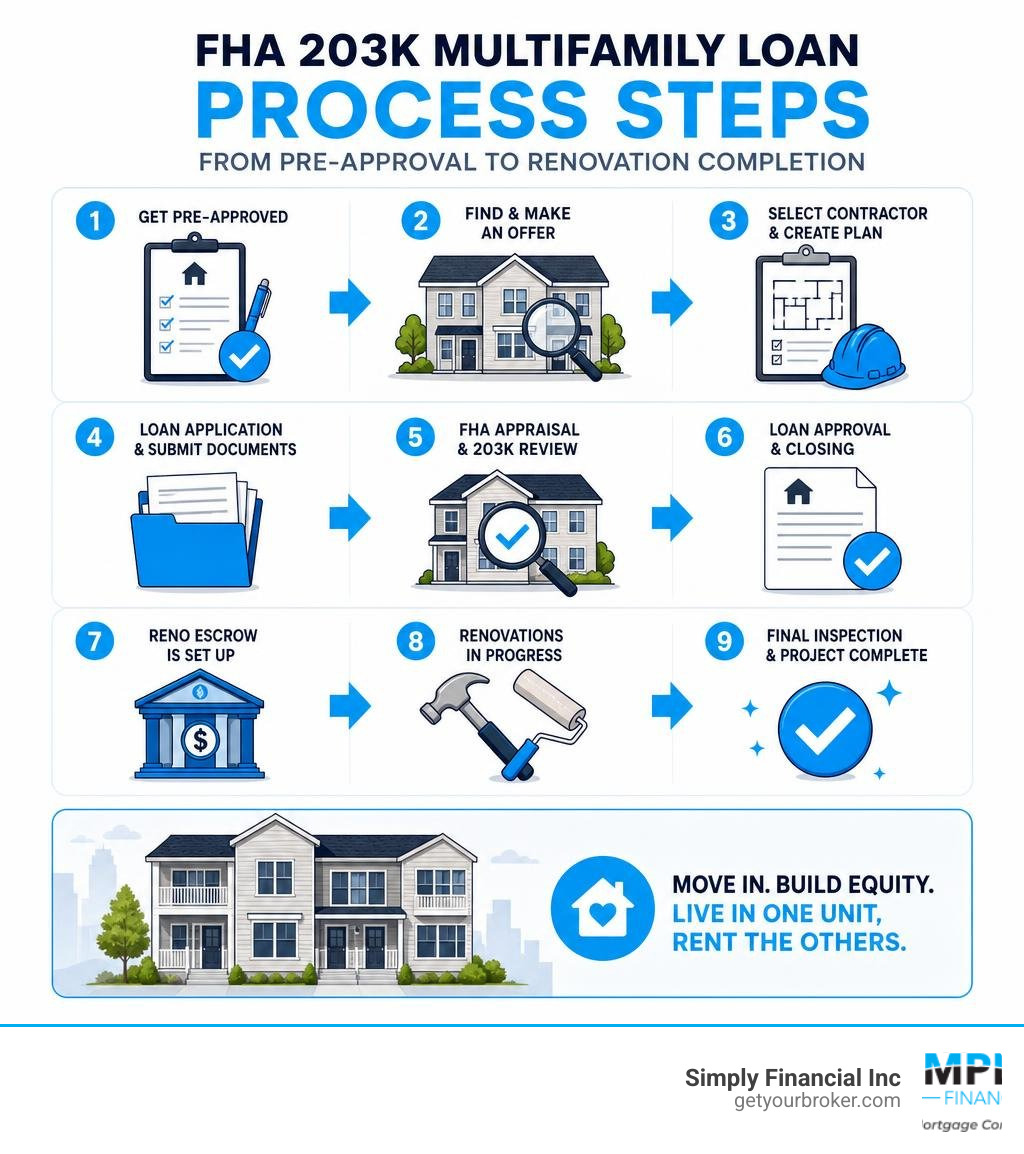
This is where the fha 203k loan multifamily program steps in to save the day. Governed by the official HUD 203(k) Program Guidelines, this loan allows lenders to insure the mortgage before the rehabilitation is complete.
Instead of requiring two separate loans — a short-term, high-interest construction loan and a permanent mortgage — the FHA 203k wraps everything into a single, long-term, fixed-rate mortgage. The loan amount is based on the “After-Repair Value” (ARV) of the property rather than its current, run-down condition. At closing, the purchase price is paid to the seller, and the remaining funds are held in a secure escrow account to pay the contractors as they complete the work.
For multifamily buyers, this means you can acquire a 2-, 3-, or 4-family building, plan a comprehensive renovation of all units, and begin generating rental income from modernized spaces that command top-market rents.
Standard 203(k) vs. Limited 203(k) for Multifamily Properties
The FHA 203k program is split into two distinct tracks depending on the scale and nature of the renovations your multifamily property requires. Choosing the right path is crucial for setting your budget and timeline.
The Limited 203(k) Program
The Limited 203(k) program is designed for minor, non-structural updates. For FHA case numbers assigned, the maximum repair budget is capped at $75,000.
Because the repairs are minor, there is no requirement to hire an official HUD consultant, which can save you time and administrative fees. However, you must still use licensed contractors, and you cannot make any structural alterations. If you need to replace carpet, paint the units, install new appliances, or upgrade the HVAC systems in your duplex, the Limited 203(k) is an excellent, streamlined option.
Note: While the official cap is $75,000, keep in mind that mandatory contingency reserves and administrative fees are deducted from this total, meaning your actual maximum budget for physical materials and labor is closer to $62,000 to $65,000.
The Standard 203(k) Program
If your multifamily property requires structural repairs — such as fixing a damaged foundation, moving load-bearing walls, adding or removing units, or completely gutting the plumbing and electrical systems — you must use the Standard 203(k) program.
The Standard program has no official maximum repair limit other than the overall FHA loan limits for your county. It does, however, require a minimum renovation budget of $5,000. Under the Standard program, you are required to work with a designated HUD 203(k) consultant. This consultant acts as an independent inspector, helping you draft the official architectural write-up, verify contractor bids, and oversee the release of escrow funds (draws) as construction progresses.
| Feature | Limited 203(k) | Standard 203(k) |
|---|---|---|
| Maximum Repair Budget | $75,000 | No hard limit (up to local FHA loan caps) |
| Minimum Repair Budget | None | $5,000 |
| Structural Repairs? | No | Yes (foundation, load-bearing walls, etc.) |
| HUD Consultant Required? | No (Optional) | Yes (Mandatory) |
| Can you alter unit count? | No | Yes (e.g., converting a triplex to a duplex) |
| Mortgage Payment Escrow? | No | Yes (up to 6 months of payments if uninhabitable) |
Eligibility and Requirements for Multi-Unit Properties
Financing a multi-unit property with an fha 203k loan multifamily requires meeting specific personal financial standards as well as property-specific rules.
To qualify for the minimum 3.5% down payment, FHA guidelines require a minimum credit score of 580. If your credit score falls between 500 and 579, you may still qualify, but you will be required to put down a 10% down payment.
That while these are the baseline federal requirements, individual lenders often apply their own “overlays” (stricter internal rules). It is common to see lenders require a minimum score of 620 or 640 for multifamily renovation loans due to the increased complexity of the transaction.
When planning your purchase, you must also keep an eye on Current Mortgage Rates for FHA Loans and local FHA loan limits. Because you are buying a multi-unit property, the maximum amount you can borrow is significantly higher than it is for a single-family home.
For 2025/2026, the standard FHA loan limits in low-cost areas are:
- Duplex (2 Units): $637,950
- Triplex (3 Units): $771,050
- Fourplex (4 Units): $958,350
In high-cost markets, such as Chicago IL or coastal areas of Florida, these limits can scale up past $1.2 million, allowing you to buy and renovate substantial buildings with very little out-of-pocket cash. For a detailed breakdown of how these limits apply to investment strategies, consult our FHA Investment Property Loan Guide 2026.
Owner-Occupancy Rules for an FHA 203k Loan Multifamily
The most important rule of the FHA 203k program is the owner-occupancy covenant. FHA loans are designed to promote homeownership, not to fund hands-off real estate syndicates or fix-and-flip businesses.
To legally use an fha 203k loan multifamily mortgage, you must sign an occupancy agreement certifying that you will occupy one of the units as your primary residence for at least 12 months. You must move into the property within 60 days of closing (or within 60 days of the completion of renovations if the property is determined to be uninhabitable during construction).
Falsifying your occupancy intentions is a federal offense (occupancy fraud). However, once you have fulfilled your 12-month occupancy requirement, you are legally free to move out, rent out your remaining unit, and convert the entire building into a fully passive investment property.
How to Qualify with Rental Income using an FHA 203k Loan Multifamily
One of the greatest financial hacks of multifamily investing is that the FHA allows you to use the projected rental income from the other units in the building to help you qualify for the mortgage. This can drastically lower your debt-to-income (DTI) ratio, allowing you to qualify for a much larger loan than your personal salary would normally support.
Here is how the calculation works:
- The Appraisal (Form 1025): The lender will order a Small Residential Income Property Appraisal (Form 1025). The appraiser will evaluate the property and determine the fair market rent for each of the units based on local rental comparables.
- The 75% Rule: The FHA allows the underwriting team to count 75% of this projected market rent as active income for you. The remaining 25% is subtracted as a “vacancy and maintenance factor” to ensure your numbers are realistic.
- The Self-Sufficiency Test (for 3-4 Units): If you are purchasing a 3-unit (triplex) or 4-unit (fourplex) property, the property must pass the FHA Self-Sufficiency Test. This rule dictates that the net rental income generated by all units (including your own, using projected market rent) must be greater than or equal to the total monthly mortgage payment (Principal, Interest, Taxes, Homeowners Insurance, and Mortgage Insurance Premium). Duplexes are exempt from this test, making them slightly easier to finance in high-priced neighborhoods.
Eligible Repairs and the Role of the 203(k) Consultant
The FHA 203k loan is highly versatile, but the funds cannot be used for luxury additions like outdoor swimming pools or tennis courts. The primary focus of the program is to bring properties up to the FHA’s Minimum Property Standards (MPS) while allowing for modern aesthetic upgrades.
Eligible repairs under the program include:
- Structural alterations, foundation repairs, and basement waterproofing.
- Major systems upgrades (plumbing, electrical, heating, and central air conditioning).
- Roofing, siding, gutters, downspouts, and wind-resistant window replacements.
- Complete kitchen and bathroom remodeling for all units.
- Lead-based paint abatement, mold remediation, and health/safety hazard elimination.
- Accessibility modifications for disabled tenants.
- Converting a building’s layout (e.g., turning a non-conforming 3-unit back into a legal duplex).
To navigate this detailed construction process, the Standard 203k program introduces the HUD 203(k) Consultant. This professional is a licensed architect, contractor, or home inspector who has been certified by HUD.
The consultant will visit the property to perform a feasibility study, draft a detailed “Work Write-Up” (which serves as the official construction blueprint), and establish a realistic cost estimate. They also protect you and the lender by inspecting the contractor’s work at various stages before releasing escrowed funds. To understand how this fits into the broader legal and administrative framework, you can read about the FHA 203k Rehab Loan Process.
All work must be completed by licensed and insured contractors. Your lender must approve the contractors before closing, ensuring they have the financial stability and clean licensing records required to finish the job within the FHA’s strict 12-month completion window.
Pros and Cons of FHA 203(k) vs. Alternative Financing
Before committing to an fha 203k loan multifamily project, it is wise to compare it against conventional and commercial financing options.
The Pros:
- Unmatched Leverage: You can buy a multi-unit property with only 3.5% down. Conventional loans for 2-4 unit properties typically require a 15% to 25% down payment, which can translate to hundreds of thousands of dollars in high-cost cities.
- Cheaper Interest Rates: Historically, FHA mortgage interest rates run about 0.50% to 0.75% lower than conventional interest rates.
- All-in-One Closing: You avoid the double closing costs, double appraisals, and high interest rates associated with traditional construction-to-permanent loans.
The Cons:
- Mortgage Insurance Premium (MIP): FHA loans require both an upfront MIP of 1.75% (which can be rolled into the loan) and an annual MIP (ranging from 0.55% to 0.85%) that lasts for the entire life of the loan if you put down less than 10%.
- Complex Process: The paperwork is extensive, and coordinating between the seller, lender, HUD consultant, and contractors can delay closing. While a standard home loan can close in 30 days, a 203k loan typically takes 45 to 60 days.
- Strict Property Requirements: The property must pass the FHA’s safety checks, and 3-4 unit properties must pass the strict self-sufficiency test.
For buyers looking at larger properties or those who have more capital, exploring a HUD 223(f) Loan Comparison can provide context on how commercial multifamily financing operates. To see a full menu of your borrowing pathways, check out our comprehensive guide to Mortgage Loan Options.
Frequently Asked Questions about Multifamily 203(k) Loans
Navigating the rehabilitation mortgage landscape can bring up several technical questions. Here are the answers to the most common queries we receive.
Can I use an FHA 203(k) loan for a 5+ unit building?
No. The FHA 203(k) loan is strictly a residential program limited to properties with 1 to 4 units.
If you want to buy a building with 5 or more units, you are entering commercial real estate territory. Financing a 5+ unit building requires commercial underwriting, which focuses primarily on the building’s financial performance (Debt Service Coverage Ratio) rather than your personal debt-to-income ratio. For projects of this scale, developers must use commercial FHA programs, such as the Section 221(d)(4) for new construction or the Section 223(f) for acquisitions, as detailed in the official FHA Multifamily Projects Handbook.
Can I do the renovation work myself (DIY)?
Generally, no. The FHA requires all work to be completed by professional, licensed, and insured contractors to ensure structural integrity and timely completion.
The only exception is if you are a professional contractor by trade and can provide documented proof of your licensing, experience, and financial capacity to the lender’s satisfaction. Even if approved for a DIY “Self-Help” agreement, you are only allowed to finance the cost of raw materials — you cannot pay yourself for labor or pocket any of the renovation cash.
What happens if the renovation costs exceed the budget?
To prevent projects from stalling due to unexpected construction surprises (like finding hidden water damage behind a shower wall), the FHA requires a mandatory contingency reserve.
A contingency reserve of 10% to 20% of the total repair estimate must be built directly into your initial loan budget. If your contractor uncovers an unforeseen issue, the HUD consultant can submit a change order to release these contingency funds. If the renovation is completed successfully without using the reserve, the remaining contingency money is applied directly to your mortgage principal, lowering your overall debt.
Conclusion
The fha 203k loan multifamily program is a premier tool for building long-term wealth. By combining the low down payment of an FHA loan with the ability to finance major renovations, you can buy a duplex, triplex, or fourplex, renovate it to modern standards, and let your tenants pay down your mortgage.
At Simply Financial Inc, we believe that securing a mortgage shouldn’t feel like a second job. We specialize in providing a seamless, expert-guided, and stress-free mortgage experience for buyers throughout Illinois and Florida. Whether you are walking through our doors at 5632 W Lawrence Ave in Chicago IL, or applying online from the beaches of Florida, our experienced loan officers are ready to help you navigate the 203(k) process from start to finish.
Ready to explore your options and turn a fixer-upper into a cash-flowing engine? Contact us today, or read more about our localized Chicago Rehab Loan Options to start your real estate investing journey.