

The Real Answer to Using an FHA Investment Property Loan (And Why It’s More Useful Than You Think)
Most people hear “FHA loan” and think first-time homebuyer starter home. But here’s what fewer people know: FHA loans can be a powerful entry point into real estate investing — if you understand the rules.
Quick answer for searchers:
- FHA loans cannot be used to buy a pure investment property you won’t live in
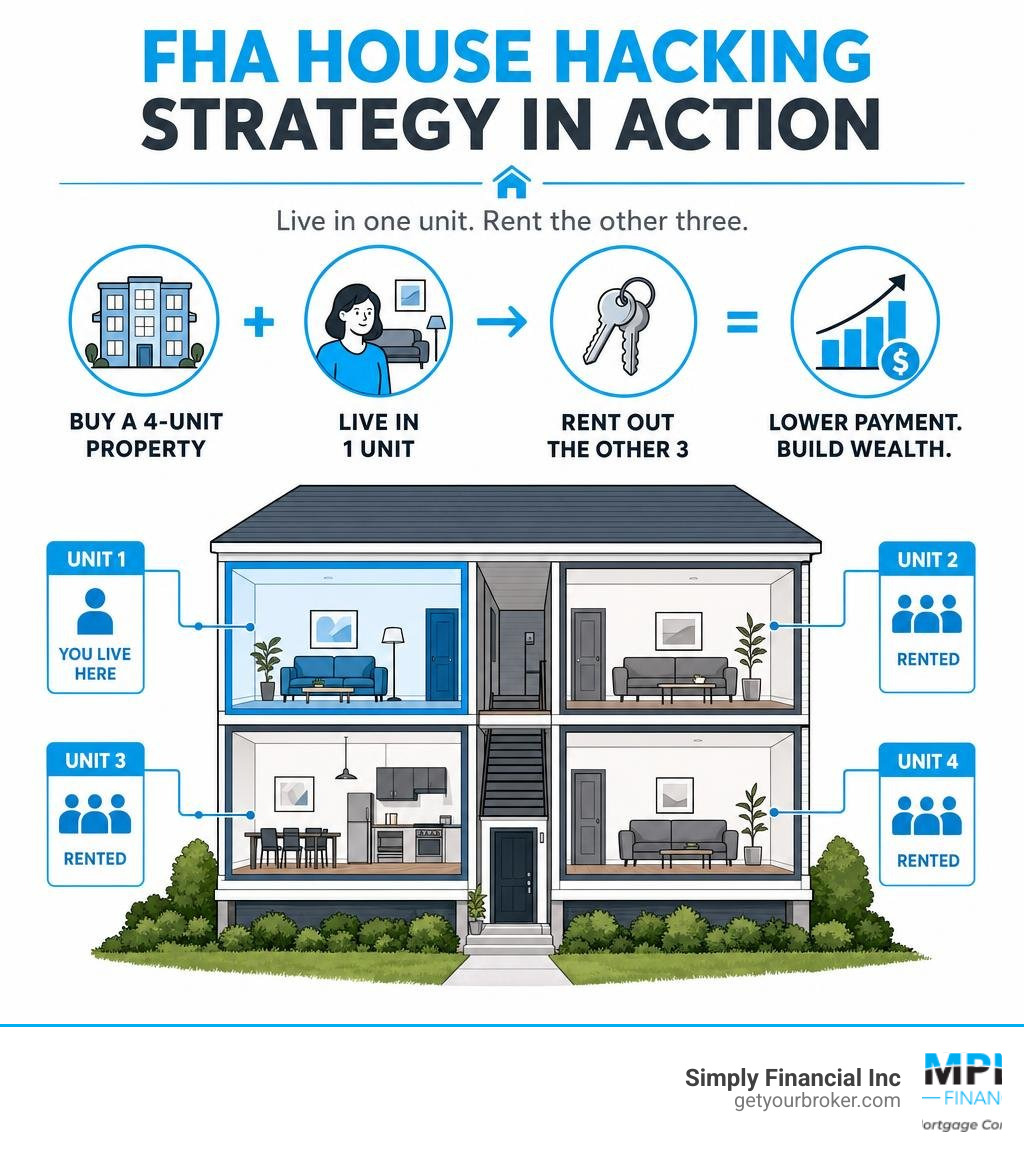
- They can be used to buy a 2-, 3-, or 4-unit property — as long as you live in one unit
- You must move in within 60 days of closing and stay for at least one year
- Down payment is as low as 3.5% (with a 580+ credit score)
- After the one-year occupancy period, you can move out and rent all units
This strategy — buying a multifamily home, living in one unit, and renting the others — is called house hacking. And it’s one of the most accessible ways to start building rental income without needing a 20-25% down payment like a conventional investment loan requires.
The catch? The rules are strict. And misunderstanding them — or worse, ignoring them — can lead to serious legal problems, including occupancy fraud.
This guide breaks down exactly how FHA multifamily financing works, what it costs, where the limits are, and whether it’s the right move for your situation.
What is an FHA Investment Property Loan?
To understand how to use an fha investment property loan, we first have to clear up a major myth. The Federal Housing Administration (FHA) does not offer a loan program designed specifically for hands-off real estate investors. You cannot walk into our office at Simply Financial Inc and ask for an FHA loan to buy a rental house down in Florida or a condo in Chicago that you plan to rent out while you live elsewhere.
Instead, the FHA loan program is designed to promote homeownership. That means it comes with strict primary residence occupancy rules. To secure FHA financing, you must sign an affidavit promising that you will occupy the property as your primary residence.
However, the “loophole” (which is actually an intentional policy feature) is that the FHA defines a “primary residence” as any residential property containing up to four units, provided the borrower occupies one of those units.
By purchasing a duplex, triplex, or fourplex, you can secure FHA financing with a minimal down payment, live in one unit, and legally lease out the remaining units to tenants. This allows you to offset your mortgage payment with rental income, effectively “hacking” your living expenses while building equity.
To learn more about how this works in local markets, check out our guide on the FHA Loan Chicago and read this breakdown of FHA Loan for Investment Property: Rules and Strategies.
The FHA Investment Property Loan Occupancy Requirements
The FHA is incredibly clear about its occupancy rules. If you use an FHA loan to purchase a property, you must:
- Move into the property as your primary residence within 60 days of closing.
- Maintain residency in that unit for a minimum of one year (365 days).
Failing to meet these guidelines without a legally recognized exception is considered occupancy fraud. Occupancy fraud is a serious federal crime with steep penalties, including hefty fines and potential jail time. Lenders do verify occupancy, so trying to bypass this rule is never worth the risk.
Are there exceptions that allow you to move out before the 365-day mark? Yes, but they are handled on a strict case-by-case basis. Acceptable exceptions generally include:
- Job Relocation: You are transferred by your employer to a new location that is at least 100 miles away.
- Family Size Increase: Your family grows (e.g., twins on the way) to the point where the current unit no longer complies with local housing density laws.
- Co-borrower Situations: A divorce or legal separation requires one borrower to vacate the property.
Outside of these verified life changes, you must complete your 12 months of occupancy before converting the entire building into a non-owner-occupied rental property.
Multi-Unit Properties: Duplex, Triplex, and Fourplex Rules
If you want to maximize your rental income, you can target properties with up to four units. However, the property must meet specific structural and zoning requirements to qualify for an FHA loan:
- Legally Zoned: The property must be legally recorded as a 1- to 4-unit residential dwelling.
- Self-Contained Units: Each unit must have its own independent entrance, a fully functioning kitchen, and its own bathroom facilities.
- No Commercial Use Restrictions: You cannot use an FHA loan to buy a boarding house, a bed and breakfast, or any property designed primarily for transient (short-term) occupancy of less than 30 days.
To dive deeper into the mechanics of managing and qualifying for these properties, you can explore the Ultimate Guide to FHA Loan for Rental Property.
Financial and Credit Requirements for FHA Multifamily Loans

One of the main reasons we guide clients toward FHA financing is its highly forgiving underwriting criteria. If you were to apply for a conventional investment property loan in Illinois or Florida, you would likely need a credit score above 680 and a minimum down payment of 20% to 25%.
With an FHA loan, those barriers are significantly lowered. You can view current trends on our Current Mortgage Rates for FHA Loans page and learn about our Low Down Payment Mortgage Chicago options.
Down Payment and Credit Score Thresholds
FHA down payment requirements are directly tied to your credit score:
- 580 FICO or Higher: You qualify for the minimum down payment of 3.5%.
- 500 to 579 FICO: You can still qualify, but you must put down at least 10%.
While a 3.5% down payment on a duplex or triplex is an incredible deal, you must also consider cash reserves. If you are buying a single-family home with an FHA loan, the lender may not require you to have any cash left over after closing.
However, for 3-unit and 4-unit properties, the FHA strictly requires 3 months of PITI reserves (Principal, Interest, Taxes, and Insurance) to be sitting in your bank account after you pay your down payment and closing costs. This ensures you can cover the mortgage if a tenant fails to pay rent.
Debt-to-Income (DTI) and the Self-Sufficiency Test
To qualify for an FHA loan, your Debt-to-Income (DTI) ratio should ideally remain at or below 43%, though automated underwriting systems can sometimes approve DTIs up to 50% if you have strong compensating factors (like high cash reserves or excellent credit).
Here is the best part: The FHA allows you to use 75% of the projected rental income from the tenant-occupied units to help you qualify.
For example, if you are buying a duplex and the appraiser estimates the other unit will rent for $2,000 a month, we can add $1,500 (75% of $2,000) directly to your qualifying monthly income. This drastically increases your purchasing power.
However, if you are buying a 3-unit (triplex) or 4-unit (fourplex) property, you must pass the FHA’s strict Self-Sufficiency Test.
Under this rule, the net rental income of the property (calculated as 75% of the estimated gross market rent of all units, including the one you plan to live in) must be greater than or equal to the total monthly PITI payment.
If the monthly mortgage payment is $4,000, but 75% of the total projected rent is only $3,800, the property fails the test, and the FHA will not insure the loan. Because duplexes are exempt from this test, they are often much easier to finance in higher-interest-rate environments.
2026 FHA Loan Limits: Single-Family vs. Multi-Unit Properties
Every year, the federal government adjusts FHA loan limits to keep pace with changing home values. Because multi-unit properties cost more to construct and purchase, the FHA substantially increases the maximum loan amount for 2-, 3-, and 4-unit properties.
This means you can borrow significantly more money with an FHA loan than you could with a standard conventional loan limit. Below is a comparison of standard and high-cost county limits for 2026:
| Property Units | Standard County Limit (2026) | High-Cost County Limit (2026) |
|---|---|---|
| 1-Unit (Single-Family) | $832,750 | $1,200,000+ |
| 2-Unit (Duplex) | $1,066,250 | $1,500,000+ |
| 3-Unit (Triplex) | $1,288,750 | $1,800,000+ |
| 4-Unit (Fourplex) | $1,602,250 | $2,403,375 |
Note: High-cost limits apply to expensive metro areas, such as certain high-value ZIP codes in South Florida or premium neighborhoods in Chicago.
These generous loan limits make it highly feasible to purchase a substantial, cash-flowing multifamily property with very little money out of pocket. For more details on utilizing these limits, read about Using FHA Loans for Investment Properties.
The True Cost of FHA Financing: Upfront and Annual MIP

While the low down payment of an FHA loan is highly attractive, it comes with a financial trade-off: Mortgage Insurance Premiums (MIP). Because the government is insuring the lender against the risk of you defaulting, they require you to pay for this protection.
There are two types of MIP you must pay:
- Upfront MIP (UFMIP): This is equal to 1.75% of your total loan amount. It is charged at closing but does not have to be paid in cash; most buyers choose to roll this cost directly into their total loan balance.
- Annual MIP: This is an ongoing monthly fee built into your mortgage payment. It ranges from 0.45% to 1.05% of the loan amount annually, depending on your loan-to-value (LTV) ratio, the loan term, and the total amount borrowed. For most buyers putting down 3.5% on a 30-year mortgage, the annual MIP sits around 0.55% to 0.85%.
The Lifetime MIP Rule: If you put down less than 10% on an FHA loan, the annual MIP never goes away. It remains on the loan for the entire 30-year term.
The only way to eliminate this monthly cost is to eventually refinance the mortgage into a conventional loan once you have built up at least 20% equity in the property. Fortunately, as your tenants pay down your principal balance and property values appreciate, refinancing out of your FHA loan is a common and highly effective exit strategy.
FHA Loans vs. Conventional and DSCR Loans for Investors
If you are serious about building a real estate portfolio, you need to know how the fha investment property loan strategy compares to other popular financing options. Every loan product has its place depending on your cash reserves, credit profile, and long-term goals.
Here is a side-by-side comparison of FHA loans, Conventional Investment Loans, and DSCR (Debt Service Coverage Ratio) Loans:
- FHA Multifamily Loans: Best for beginners or capital-constrained buyers. You only need a 3.5% down payment and a 580 credit score. However, you are legally required to live in the property for a year, you cannot buy the home under an LLC, and you have to deal with permanent MIP.
- Conventional Investment Loans: Best for buyers who have cash but want lower interest rates. These require a 15% to 25% down payment and a credit score typically above 640. You do not have to live in the property, but you still have to verify your personal income (W-2s, tax returns) and maintain a low personal DTI.
- DSCR Loans: Best for scaling a portfolio rapidly. These loans require a 20% to 25% down payment, but they do not require any personal income verification. Lenders do not look at your tax returns, W-2s, or employment history. Instead, they qualify the loan based entirely on whether the property’s rental income covers the monthly mortgage payment. You can close these loans under an LLC to protect your personal assets, and there are no limits on how many properties you can finance.
For experienced investors looking to skip personal underwriting entirely, you can review the DSCR Investor Solutions 3 Guidelines and learn more about our local options for a Chicago Investment Property.
Frequently Asked Questions about FHA Investment Property Loans
Can you use an fha investment property loan for a non-owner-occupied property?
No. There is no such thing as a non-owner-occupied FHA loan. To use an FHA loan, you must occupy the property as your primary residence. The only exceptions are rare, case-by-case scenarios such as a job relocation, an expanding family that outgrows the current home, or a co-borrower divorce. Trying to buy a rental property with an FHA loan without intending to live there is occupancy fraud.
How long do you have to live in an FHA multi-unit property before renting it out entirely?
You must occupy the property for at least one year (365 days). After you have completed your 12 months of owner-occupancy, you are legally permitted to move out of your unit, rent it to a tenant, and convert the entire 2- to 4-unit building into a fully hands-off rental property.
Can you buy an FHA investment property under an LLC?
No. FHA guidelines require the borrowers to be individual human beings whose credit and personal income can be verified. You cannot close or vest an FHA loan under a business entity like an LLC or a corporation. If liability protection is your primary goal, you will need to look into conventional or DSCR loan options.
Conclusion
Using an fha investment property loan via the house hacking strategy is one of the smartest wealth-building moves you can make. It allows you to break into the real estate market with a tiny 3.5% down payment, let your tenants pay down your mortgage, and set yourself up for long-term financial freedom.
At Simply Financial Inc, we specialize in making this process seamless, expert-guided, and entirely stress-free. Whether you are looking to house hack a duplex in Chicago, purchase a triplex in Florida, or explore alternative commercial and DSCR options, our expert team is here to guide you every step of the way.
Ready to take the next step toward financial independence? Explore Chicago Investment Property Options with us today and let’s get your investment journey started!