

Why an FHA Loan for a Mobile Home and Land Could Be Your Path to Homeownership
Getting an fha loan for mobile home and land is one of the most accessible ways to finance a manufactured home — especially if you have a lower credit score or limited savings for a down payment.
Here is a quick answer to what most buyers want to know:
| What You Want to Do | Best FHA Option | Min. Down Payment | 2026 Loan Limit |
|---|---|---|---|
| Buy home + land together | FHA Title II | 3.5% (580+ credit) | $541,287 |
| Buy home only (no land) | FHA Title I | 5% (580+ credit) | $105,532–$193,719 |
| Buy land only | FHA Title I | 5% (580+ credit) | $43,377 |
| Buy home + land (Title I) | FHA Title I | 5% (580+ credit) | $148,909–$237,096 |
The short version: FHA offers two loan programs for manufactured homes. Title I works for home-only or smaller home-and-lot purchases. Title II works like a traditional mortgage when you own the land and the home sits on a permanent foundation.
But there are real rules about the home’s age, size, foundation, and how it is titled — and missing even one requirement can derail your loan.
That is where most buyers run into trouble. The process is more complex than a standard home purchase, and the paperwork can feel overwhelming without the right guidance.
This guide breaks it all down in plain language so you know exactly what to expect before you apply.
FHA Manufactured Home Guidelines: Property and Borrower Requirements
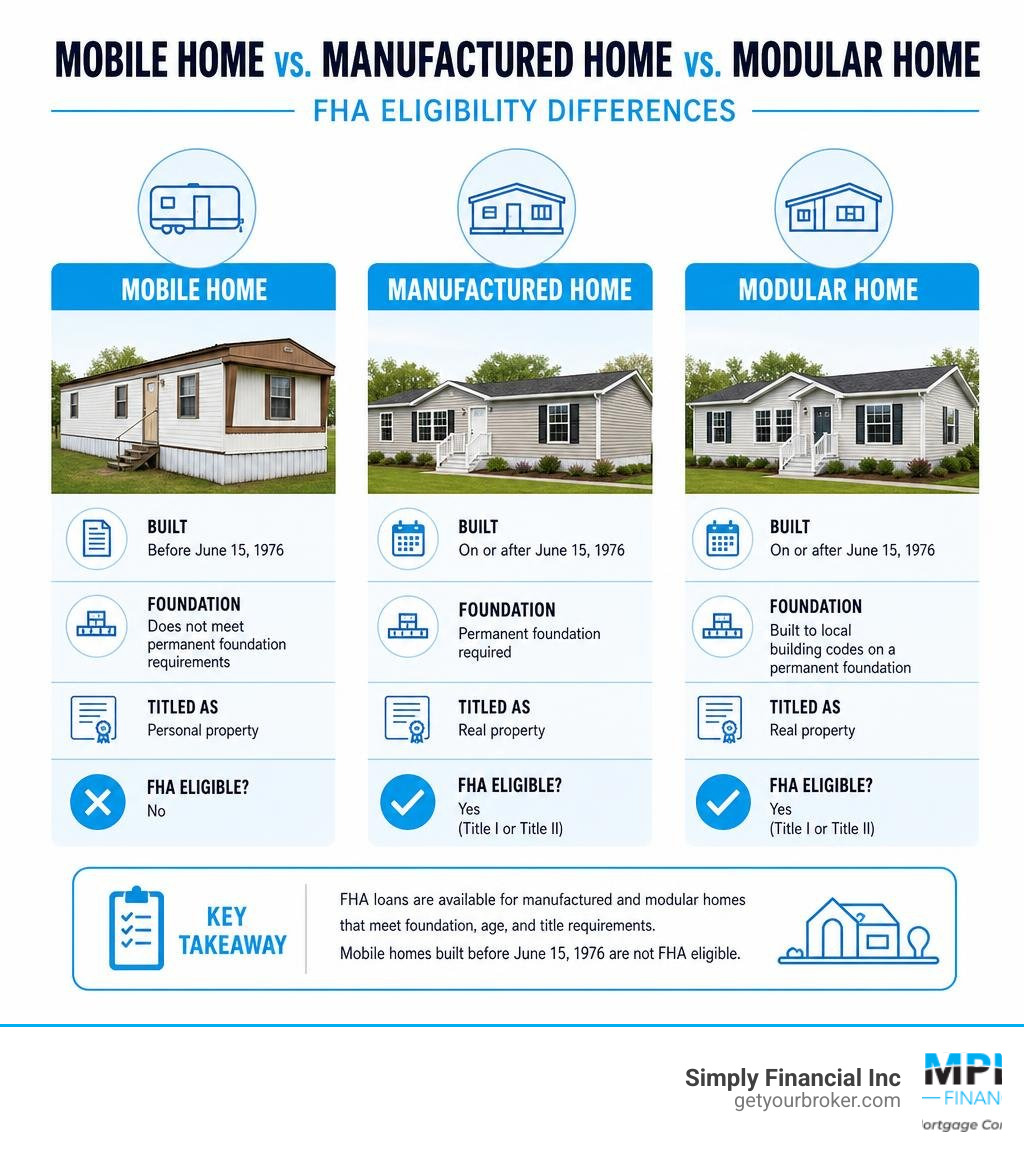
Before diving into the loan applications, we need to clarify what kind of property you are actually buying. In the eyes of the Federal Housing Administration (FHA) and mortgage lenders, there is a massive difference between “mobile,” “manufactured,” and “modular” homes.
If you are looking to secure an FHA Loan, you must understand these property definitions, as they dictate which rules apply.
- Mobile Homes: Technically, a “mobile home” refers only to factory-built housing constructed before June 15, 1976. These homes were built before national safety and construction standards were put in place.
- Manufactured Homes: These are factory-built homes constructed after June 15, 1976, under the federal HUD Code. They are built on a permanent steel chassis.
- Modular Homes: These homes are built in sections at a factory but are assembled on-site on a permanent foundation. They are built to state and local building codes rather than federal HUD codes. For financing purposes, modular homes are treated exactly like traditional, site-built homes.
To ensure your home is eligible for government-backed financing, you must follow the strict Rules to Know for FHA Manufactured Home Loans. Let’s look at the exact standards your property must meet.
HUD Code and the June 15, 1976 Cutoff
If the home you want to buy was built before June 15, 1976, it cannot be financed with an FHA loan. No exceptions, no loopholes.
For homes built after this cutoff date, the FHA requires physical proof of compliance with the Federal Manufactured Home Construction and Safety Standards (commonly known as the HUD Code). This proof comes in two forms:
- The HUD Certification Label (Red Tag): This is a small, metal plate affixed to the exterior of each transportable section of the manufactured home. If you are buying a double-wide, there should be two red tags.
- The HUD Data Plate: This is an interior paper document, usually pasted inside a kitchen cabinet, near the main electrical panel, or in a bedroom closet. It contains manufacturing details, wind zone maps, and roof load capacities.
If these labels have been painted over, removed, or lost, you will face major roadblocks during the appraisal process. We always advise our clients in Illinois and Florida to locate these tags before making an offer.
Minimum Size, Foundation, and HUD Certification Standards
Even if your home has its HUD tags, it must still pass several physical and legal property standards to qualify for an FHA loan:
- Minimum Size: The home must have a minimum floor area of at least 400 square feet. This generally means most single-wides and all double-wides qualify, but tiny homes on wheels do not.
- Permanent Foundation: The home must be permanently attached to a foundation system designed in accordance with the HUD Permanent Foundations Guide for Manufactured Housing. This foundation can consist of concrete piers, slabs, or crawl spaces.
- Engineering Certification: A licensed professional engineer must inspect the foundation and certify that it meets these strict HUD guidelines.
- Real Estate Classification: For standard Title II mortgage financing, the home must be legally classified and taxed as real property (real estate) rather than personal property (like a car or boat).
- Site Utilities: The site must have proper access to water and sewage facilities (either municipal hookups or approved private septic and well systems) and have access to an all-weather road.
Credit Scores, Down Payments, and Debt-to-Income (DTI) Limits
Now let’s talk about you, the borrower. FHA loans are famous for their flexible credit guidelines, which is why we frequently recommend them to first-time buyers looking at Current Mortgage Rates for FHA Loans.
The financial requirements for an FHA manufactured home loan depend on your credit score:
- Credit Score of 580 or Higher: You qualify for the minimum down payment of 3.5%.
- Credit Score Between 500 and 579: You can still qualify, but you must put down at least 10%.
- Debt-to-Income (DTI) Ratio: Generally, your front-end DTI (housing costs) should not exceed 31%, and your back-end DTI (total monthly debts) should not exceed 43%. However, if the home is certified as Energy Star compliant, the FHA allows these ratios to stretch to 33% and 45% respectively.
If you already own the land you plan to place the home on, you may be able to use your land equity to cover your down payment requirements!
FHA Title I vs. Title II: Choosing an FHA Loan for Mobile Home and Land
When shopping for an fha loan for mobile home and land, you must choose between two distinct programs: Title I and Title II.
Here is a side-by-side comparison of how these two programs stack up in 2026:
| Feature | FHA Title I Loan | FHA Title II Loan |
|---|---|---|
| Property Type | Personal property or real estate | Real estate only |
| Land Ownership | Owned or leased land | Owned land only |
| Max Loan Term | 15 to 25 years | Up to 30 years |
| 2026 Combination Limit | $148,909 (Single-wide) / $237,096 (Double-wide) | $541,287 (In most IL/FL areas) |
| Upfront MIP | Up to 2.25% | 1.75% |
| Annual MIP | Up to 1.0% | 0.85% (Depends on term/LTV) |
| FHA Loss Insurance | Insures up to 90% of lender loss | Insures 100% of lender loss |
Choosing the right path depends on whether you plan to buy the land, lease a lot in a community, or convert your home into permanent real estate. For official government program details, you can read the Financing Manufactured Homes (Title I) – HUD resources.
FHA Title I: Financing a Manufactured Home Without Land
The FHA Title I program is unique because it allows you to finance a manufactured home even if you do not own the land it sits on. Under Title I, the home is typically financed as personal property (similar to a chattel loan), meaning you do not have to go through the complex legal process of retiring the home’s vehicle title.
For 2026, the updated FHA Title I loan limits are:
- Single-wide home only: $105,532
- Double-wide home only: $193,719
- Single-wide with land: $148,909
- Double-wide with land: $237,096
- Lot-only financing: $43,377
The Catch: Because Title I loans only insure up to 90% of the lender’s loss (compared to 100% for Title II), many lenders do not offer them. If you do find a Title I lender, expect shorter loan terms (usually 20 years for a home-only loan) and slightly higher mortgage insurance premiums (up to 2.25% upfront and 1.0% annually).
FHA Title II: The Premier FHA Loan for Mobile Home and Land Option
If you want the lowest interest rates, a traditional 30-year term, and the ability to buy a larger plot of land, FHA Title II is the gold standard. To learn more about how this mortgage-style program operates, check out FHA Loan for Mobile Home: How It Works and How to Qualify.
Under Title II, the home and the land are bundled together into a single real estate transaction. Because the home is permanently affixed to the land and classified as real property, the FHA treats it almost exactly like a site-built home.
This means you can access the standard FHA Title II loan limits, which reach $541,287 in most areas of Illinois and Florida as of 2026. You also benefit from lower mortgage insurance costs (1.75% upfront and 0.85% annually) and standard 30-year amortization schedules, making your monthly payments much more affordable.
Leased Land vs. Owned Land Requirements
Can you still get an FHA loan if your manufactured home is located in a mobile home park or on leased land? Yes, but the guidelines are highly specific:
- Minimum Lease Term: The HUD guidelines state that if you lease the lot, the lease must have an initial term of at least three years.
- Termination Notice: The lease agreement must state that you will receive at least 180 days advance written notice if the landlord intends to terminate your lease.
- Site Suitability: The park or leased community must meet local zoning requirements, have adequate water and sewage hookups, and be accessible by municipal or emergency vehicles via all-weather roads.
Because many mobile home parks only offer one-year leases, finding an eligible leased lot can be tricky. This is why buying both the home and the land together is usually the smoothest path to approval.
Securing an FHA Loan for Mobile Home and Land: Step-by-Step

If you are pursuing an FHA Title II loan to buy a manufactured home and land together, you must complete the title retirement process. When a manufactured home leaves the factory, it is issued a personal property title (similar to a car title) by the DMV.
To convert it into real property for a standard mortgage, you must follow these steps:
- Install the Foundation: The home must be permanently affixed to a HUD-compliant foundation.
- Get an Engineer’s Certification: Hire a licensed structural engineer to inspect the foundation and issue a compliance certificate.
- File an Affidavit of Affixture: Submit an affidavit of affixture to your county recorder’s office in Illinois or Florida. This document states that the home is now a permanent part of the land.
- Surrender the Personal Property Title: File the necessary paperwork with the state DMV to officially retire and eliminate the vehicle/chassis title.
- Reclassify the Taxes: Confirm with the local tax assessor that the home is now being taxed as real estate rather than personal property.
Pros, Cons, and Alternatives to FHA Manufactured Home Financing
While an FHA loan is an incredible tool, it is not the only way to finance a manufactured home. To make the best decision for your wallet, you should weigh the pros and cons of this program against other Mortgage Loan Options.
For a deep dive into how these programs protect lenders and borrowers alike, you can review the official FDIC guide on Manufactured Home Loan Insurance.
FHA Loans vs. Conventional Financing
Conventional manufactured home loans (such as Fannie Mae’s MH Advantage or Freddie Mac’s CHOICEHome) offer some great benefits, but they have stricter entry requirements than FHA loans.
- Down Payment: FHA requires 3.5% down; conventional loans allow down payments as low as 3% for highly qualified buyers.
- Credit Scores: FHA accepts scores down to 500. Conventional programs typically require a minimum credit score of 620, with the best interest rates reserved for those with scores above 740.
- Mortgage Insurance: FHA mortgage insurance (MIP) is required for the life of the loan if you put down less than 10%. On a conventional loan, private mortgage insurance (PMI) can be canceled once you reach 20% equity.
- Interest Rates: FHA land-home rates are highly competitive, typically ranging from 6.5% to 7.5%. This is significantly cheaper than personal property “chattel loans,” which often carry interest rates between 8% and 12% and offer much shorter repayment terms.
Alternative Options: VA, USDA, and Land-Home Loans
If an FHA loan does not quite fit your situation, we can help you explore several other government-backed land-home loan programs:
- VA Manufactured Home Loans: If you are an eligible veteran, active-duty service member, or surviving spouse, you can secure a manufactured home and land with 0% down payment and no monthly mortgage insurance.
- USDA Rural Development Loans: For properties located in designated rural areas of Illinois or Florida, USDA loans offer 0% down payment financing. Strict household income limits apply, and the manufactured home must generally be brand new to qualify for USDA financing.
- Chattel Loans: If you are placing a home in a park with a standard lease and cannot meet FHA’s 3-year lease requirement, a chattel loan is a fast, flexible alternative. However, be prepared for higher interest rates and shorter 15- to 20-year terms.
Frequently Asked Questions about FHA Manufactured Home Loans
Can you buy a mobile home with an FHA loan if it has been moved?
For FHA Title II loans, no. The home must be installed on its permanent foundation directly from the factory. If a manufactured home has been moved from its original installation site to a different piece of land, it is disqualified from FHA Title II financing.
This “moved home” rule is designed to protect the structural integrity of the home. However, some FHA Title I programs or conventional loans may still allow financing for relocated homes.
What is the minimum square footage for an FHA manufactured home loan?
The absolute minimum living area required for an FHA manufactured home loan is 400 square feet. This rule applies to both single-wide and double-wide configurations. If you are shopping for a tiny home, make sure to verify its exact square footage, as many fall just below this 400-square-foot threshold.
How long does it take to close an FHA land and home loan?
If you are doing a simultaneous purchase of a brand-new home and land together, the closing process typically takes 45 to 60 days.
However, if you are purchasing an existing manufactured home that requires a foundation inspection, engineering certification, and a manual title retirement process, the closing timeline can stretch to 75 to 150 days. Working with an experienced local appraiser and structural engineer early in the process is key to avoiding delays.
Conclusion
Buying a manufactured home is an incredible, cost-effective way to build wealth and secure a place of your own. By pairing your purchase with an FHA loan, you can enjoy low down payments, flexible credit requirements, and highly competitive interest rates.
At Simply Financial Inc, our mission is to deliver a seamless, expert-guided, and completely stress-free mortgage experience. Whether you are looking for an FHA Loan Chicago to buy a property near our office at 5632 W Lawrence Ave Chicago IL, or you are searching for a sunny plot of land in Florida, we are here to help you navigate the paperwork.
Ready to take the first step? Contact us today to explore your manufactured home financing options and get pre-approved!