

What Is an FHA Loan? A Quick Guide for Homebuyers
An FHA loan is a government-backed mortgage insured by the Federal Housing Administration — one of the most accessible paths to homeownership available today, especially if you have a lower credit score or limited savings for a down payment.
Here’s what you need to know at a glance:
| Feature | Details |
|---|---|
| Minimum credit score | 580 (for 3.5% down) or 500 (for 10% down) |
| Minimum down payment | 3.5% |
| Loan limits (2026) | $541,287 (low-cost) to $1,249,125 (high-cost areas) |
| Mortgage insurance | 1.75% upfront + 0.45%–1.05% annually |
| Property requirement | Primary residence only |
| Available since | 1934 |
FHA loans don’t come directly from the government. Instead, the Federal Housing Administration insures the loan, which means private lenders take on less risk — and can offer you better terms as a result.
This matters a lot if you’ve been turned down elsewhere or feel stuck because your credit isn’t perfect.
Since 1934, this program has helped millions of Americans buy homes who might not have qualified for a conventional mortgage. Whether you’re buying your first home or starting over after a financial setback, an FHA loan could be the key that opens the door.
This guide covers everything — requirements, loan types, costs, and how to apply — so you can move forward with confidence.
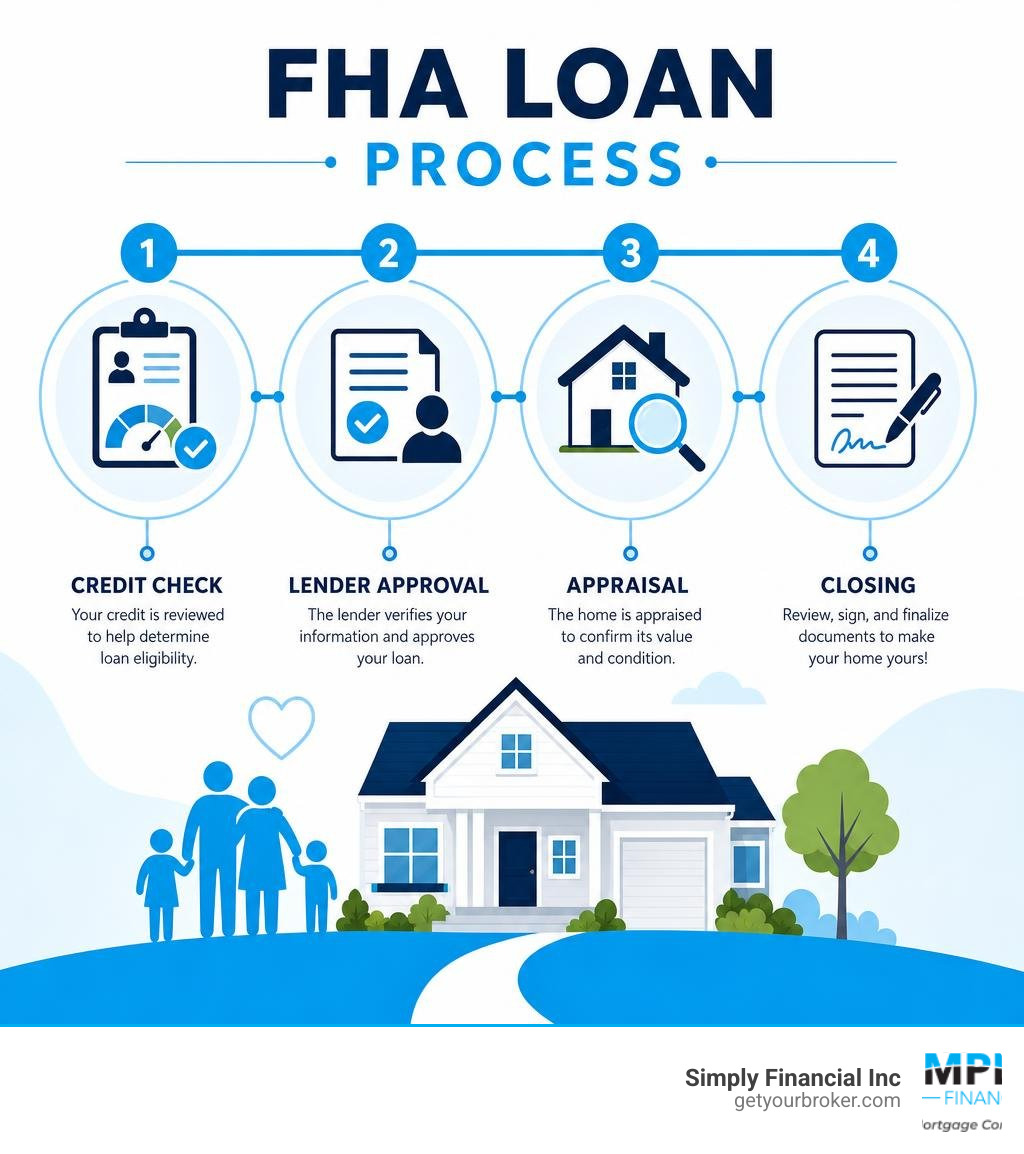
Understanding the FHA Loan: Definition and Benefits
At its core, the fha loan program is designed to make homeownership a reality for everyday people. Managed by the U.S. Department of Housing and Urban Development (HUD) through its HUD single family programs, the program operates on a simple premise: by insuring the mortgage, the federal government protects lenders against losses if a borrower defaults. This safety net allows mortgage brokers and lenders to offer highly competitive terms to buyers who do not fit the rigid mold of conventional financing.
However, there is a fundamental rule you must keep in mind: the property you buy must be your primary residence. FHA loans are not designed for real estate investors looking to flip properties or buyers seeking a cozy weekend vacation home in Florida. You must plan to move in and occupy the home within 60 days of closing.
The benefits of choosing an fha loan over other Mortgage Loan Options are substantial:
- Lenient Credit Guidelines: If your credit history has a few bumps, such as a past bankruptcy, foreclosure, or simply a low score, you are not automatically disqualified.
- Low Down Payment Options: You do not need to save 10% or 20% of the home’s purchase price. For many, a down payment as low as 3.5% is all it takes.
- Flexible Funding: The money for your down payment and closing costs does not have to come entirely from your own bank account. It can come from approved local down payment assistance programs, or even as a documented gift from family members.
To learn more about how government-backed programs can assist your transition into homeownership, you can explore the official Loans and housing assistance programs resource.
Key FHA Loan Requirements for 2026
When we guide our clients through the mortgage process, we emphasize that while the FHA program is highly flexible, it is not a “free pass.” Private lenders must verify that you have the financial capacity to repay the loan and that the property you are purchasing is safe, secure, and worth the purchase price.

Before a loan can be approved, the home must undergo a specialized inspection by an FHA-approved appraiser. This appraiser evaluates the property against strict FHA minimum property standards. Unlike a standard conventional appraisal, which primarily looks at market value, an FHA appraisal focuses heavily on safety and soundness.
The appraiser will look for potential hazards such as:
- Peeling paint (especially in homes built before 1978 due to lead risk)
- Exposed wiring or electrical hazards
- Non-functioning heating systems
- Structural damage or active roof leaks
- Termite infestations or wet crawlspaces
If the appraiser flags any safety issues, those repairs must typically be completed and re-inspected before the loan can close.
Credit Score and Down Payment Guidelines
The relationship between your credit score and your minimum down payment is straightforward. The FHA program splits qualification into two distinct tiers:
- 580 Credit Score and Higher: This is the sweet spot. If your credit score is 580 or higher, you qualify for the minimum down payment of just 3.5%.
- 500 to 579 Credit Score: You can still qualify! However, to offset the higher risk, you must provide a 10% down payment.
If your score is below 500, you are unfortunately not eligible for FHA financing at this time, but we can help you map out a strategy to build your score back up.
One of the most attractive features of an fha loan is the ability to use gift funds. If a parent, relative, or close friend wants to help you buy your home, they can gift you the down payment. However, this requires strict gift funds documentation. The donor must sign a gift letter stating that the money is a true gift and does not need to be repaid, and we must document the paper trail of the funds moving from their account to yours.
For those looking to buy in the Chicago metropolitan area, utilizing a Low Down Payment Mortgage Chicago is an excellent way to keep cash in your pocket. If you are shopping in the Sunshine State, make sure to review the Full List of Florida FHA Loan Requirements or consult the HUD Florida Homeownership Information to see how state-specific rules might apply to your purchase.
Debt-to-Income (DTI) and Income Limits
Your Debt-to-Income (DTI) ratio is a comparison of your monthly debt obligations to your gross monthly income. The FHA uses two distinct calculations:
- Front-End Ratio (Housing DTI): This is the percentage of your gross income that goes toward your mortgage payment (including principal, interest, taxes, home insurance, and mortgage insurance). The FHA generally likes to see this kept at 31% or lower.
- Back-End Ratio (Total DTI): This includes your housing payment plus all other monthly recurring debts (such as student loans, credit cards, auto loans, and personal loans). The standard limit is 43%.
However, if you have “compensating factors” — such as a high credit score, substantial cash reserves left over after closing, or a significant increase in income — we can often secure approvals for back-end DTIs up to 50% or more using automated underwriting systems.
To verify your ability to pay, you must demonstrate a stable employment history, typically spanning the last two consecutive years. We will need to collect:
- Your most recent W-2 forms
- Pay stubs covering the last 30 days
- Complete tax returns for the past two years (especially critical if you are self-employed or rely on commission income)
FHA Mortgage Insurance Explained
Because the FHA allows lower down payments and credit scores, it requires borrowers to pay mortgage insurance premiums (MIP). This insurance protects the lender if you are unable to make your payments.
There are two parts to FHA mortgage insurance, and you must pay both:
- Upfront Mortgage Insurance Premium (UFMIP): This is a one-time fee equal to 1.75% of your total loan amount. It is charged at the time of closing. While you can pay this in cash, almost all borrowers choose to roll this fee directly into their total loan balance, meaning you pay it off gradually over the life of your mortgage.
- Annual Mortgage Insurance Premium (MIP): Despite the name “annual,” this fee is divided by 12 and added to your monthly mortgage payment. The premium ranges from 0.45% to 1.05% of your loan balance, depending on your loan term (15 vs. 30 years), your loan amount, and your down payment size. For most 30-year loans with a 3.5% down payment, the annual MIP sits at 0.55%.
The FHA Mortgage Insurance Timeline
Unlike conventional private mortgage insurance (PMI), which drops off automatically once you reach 20% equity in your home, FHA mortgage insurance has stricter rules:
- If your down payment is less than 10%: You must pay the annual MIP for the entire life of the loan. The only way to get rid of it is to refinance your FHA loan into a conventional loan once you have built up 20% equity.
- If your down payment is 10% or more: Your MIP will automatically cancel after 11 years.
Types of FHA Loans Available
The FHA program is not a one-size-fits-all solution. There are several specialized loan options designed to fit different properties and financial goals.

- 203(b) Purchase Loan: This is the standard, bread-and-butter FHA loan used to purchase a move-in ready home.
- 203(k) Rehab Loan: Have you found a home with great potential but in desperate need of repairs? The 203(k) program allows you to bundle the purchase price of the home and the cost of necessary renovations into a single, convenient mortgage.
- Manufactured Housing Financing: Yes, you can use an FHA loan to finance manufactured or mobile homes, provided they meet specific structural guidelines and are permanently affixed to land you own or are purchasing.
- Title I Program: If you already own a home and need to make vital repairs or accessibility upgrades but don’t have much equity, a Title I loan can provide the necessary financing for property improvements.
Choosing the Right FHA Loan for Your Property
FHA loans are incredibly versatile when it comes to the types of properties you can buy. You can use them for:
- Single-family homes
- 1-4 unit properties (as long as you live in one of the units)
- Condominiums (the condo building must appear on the HUD condominium approval list, though we can sometimes help request individual unit approval)
- Mixed-use properties (provided that at least 51% of the total building space is dedicated to residential living)
If you are a first-time buyer in the Chicago area, exploring First Time Home Buyer Programs Chicago can open doors to local grants that pair beautifully with FHA loans to reduce your out-of-pocket costs.
The FHA Loan Refinance Programs
If you already have an FHA loan, you have access to simplified refinancing options:
- Streamline Refinance: If interest rates drop, an FHA Streamline Refinance is one of the fastest ways to lower your monthly payment. It requires no home appraisal and minimal underwriting. To qualify, you must have a history of on-time payments and have made at least six consecutive payments on your current mortgage.
- Rate-and-Term Refinance: This allows you to change the terms of your loan, such as switching from an adjustable-rate mortgage to a secure 30-year fixed-rate mortgage.
- Cash-Out Refinance: If you have built up significant equity in your home, this option allows you to refinance for more than you owe and take the difference in cash to pay off high-interest debt or make home improvements.
Comparing FHA Loans to Conventional, VA, and USDA Mortgages
To make the best decision for your family, it is helpful to see how an fha loan stacks up against other popular loan programs:
| Feature | FHA Loan | Conventional Loan | VA Loan | USDA Loan |
|---|---|---|---|---|
| Backed By | Federal Housing Administration | Fannie Mae / Freddie Mac | Dept. of Veterans Affairs | Dept. of Agriculture |
| Min. Credit Score | 500 (10% down) or 580 (3.5% down) | Typically 620 | Varies (often 580–620) | Typically 640 |
| Min. Down Payment | 3.5% | 3% (for first-time buyers) | 0% | 0% |
| Mortgage Insurance | Upfront & Annual MIP | Private Mortgage Insurance (PMI) if <20% down | None (Funding Fee applies) | Upfront & Annual Fees |
| Property Location | Nationwide | Nationwide | Nationwide | Rural areas only |
| Best For | Lower credit, modest down payment | Strong credit, 3%–20% down | Eligible Veterans & service members | Low-to-moderate income in rural areas |
While conventional loans offer the ability to avoid mortgage insurance entirely with a 20% down payment, they require much higher credit scores and have stricter debt-to-income limits. VA loans offer 0% down and no monthly mortgage insurance, but are strictly reserved for veterans, active-duty service members, and eligible surviving spouses. USDA loans also offer 0% down but are limited to specific rural geographic boundaries.
For buyers who need credit score flexibility and have a modest down payment, the fha loan remains one of the most reliable and accessible options on the market.
Frequently Asked Questions about FHA Loans
What are the 2026 FHA loan limits?
The FHA limits the maximum amount you can borrow, and these limits are updated annually based on local home prices. For 2026, the limits for a single-family (one-unit) home are:
- Low-Cost Areas: $541,287 (this applies to many counties across Illinois and Florida)
- High-Cost Areas: $1,249,125 (for expensive housing markets)
If you are looking at multi-unit properties, the loan limits are significantly higher. To find the exact limit for your specific county, you can use the official HUD mortgage limits search tool.
Can I buy a multi-unit property with an FHA loan?
Absolutely! You can use an FHA loan to buy a 2-unit, 3-unit, or 4-unit property. This is a highly popular strategy known as “house hacking.”
The catch? You must occupy one of the units as your primary residence for at least one year. You can rent out the remaining units to tenants, and we can even use that projected rental income to help you qualify for the mortgage. Purchasing multi-family homes must still fall within the FHA multifamily loan thresholds.
How do I find an FHA-approved lender?
Because FHA loans are issued by private entities, you must work with an approved lender. You can search the official HUD approved lender list to verify a lender’s status. For a comprehensive overview of how lenders operate within this program, you can review the Lender Summary on the HUD website or explore FHA and Housing Resources directly.
If you are ready to take the first step toward buying a home in Illinois or Florida, you can easily Pre-Qualify Chicago Mortgage Pre-Approval through our secure online portal to see what options are available to you.
Conclusion
Navigating the home buying process can feel overwhelming, but you do not have to do it alone. At Simply Financial Inc, we specialize in taking the complexity out of home financing. Our mission is to deliver a seamless, expert-guided, and completely stress-free mortgage experience tailored directly to your unique financial situation.
Whether you are looking to purchase a beautiful bungalow in Chicago or a sunny retreat in Florida, we are here to help you find the perfect loan program.
Ready to explore your options? Let’s talk!
- Discover how we can help you secure an FHA Loan Chicago to buy your dream home.
- Reach out to our team today at our Chicago office located at 5632 W Lawrence Ave Chicago IL, or Contact Us Chicago Mortgage Lender to start your journey toward homeownership with confidence.