

Why a Fixed Rate Mortgage Is Still the Most Popular Home Loan in America
A fixed rate mortgage is a home loan where your interest rate stays the same for the entire life of the loan — whether that’s 15 years, 30 years, or another term.
Here’s what that means in plain English:
- Your monthly principal and interest payment never changes
- You’re protected if market rates rise after you close
- It’s easier to budget because there are no surprises
- The most common terms are 15 years and 30 years
As of June 18, 2026, the average 30-year fixed rate is 6.47% and the average 15-year fixed rate is 5.81%, according to Freddie Mac’s Primary Mortgage Market Survey.
For most homebuyers — especially first-timers — the appeal is simple: you know exactly what you’re paying every month, from day one to the final payment. No guessing. No stress when you read the news about rising rates.
That predictability is a big deal when you’re already juggling inspections, paperwork, and moving boxes.
This guide covers everything you need to know: how fixed rate mortgages work, what rates look like right now, how to qualify, and which loan type fits your situation.
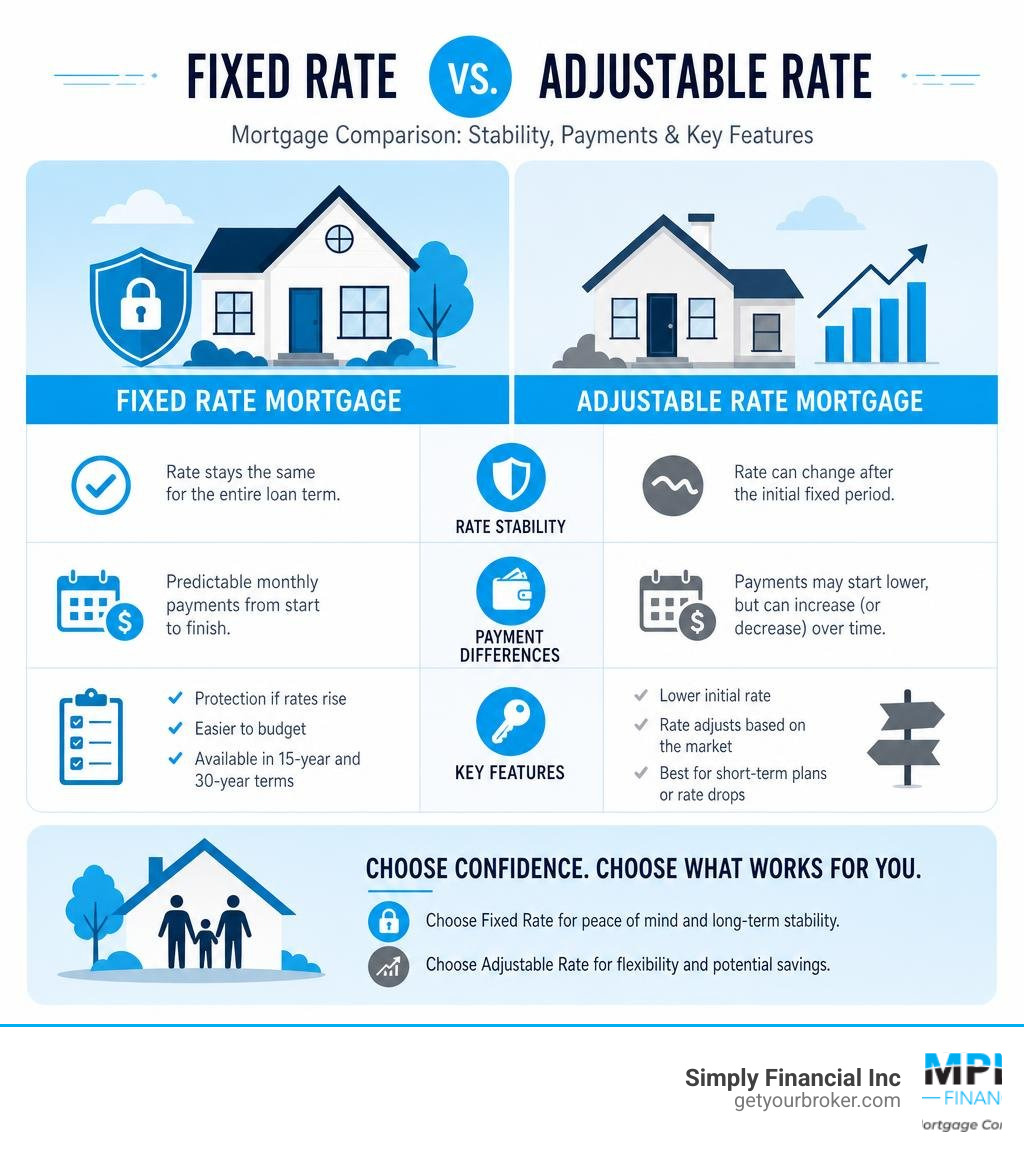
What is a Fixed Rate Mortgage?
At its core, a fixed rate mortgage is the “vanilla wafer” of the home loan world. It contains absolutely no surprises. When you sign your closing papers, the interest rate on your loan is locked in. Whether you choose a 10-year, 15-year, 20-year, or 30-year term, that rate will not budge by even a fraction of a percent.
Your monthly mortgage payment is split into two primary components: principal (the money that actually pays down the balance of your home loan) and interest (the fee the lender charges you to borrow that money). Together, these form your base monthly payment. While your local property taxes and homeowners insurance premiums may fluctuate over time, the core principal and interest portion of your payment remains completely static.
This stability makes the fixed rate mortgage an incredibly powerful tool for long-term financial planning. If you plan to settle down in a home in Chicago or a sunny neighborhood in Florida for the long haul, knowing your housing costs will stay the same for the next few decades provides unmatched peace of mind.
Fixed Rate Mortgage vs. Adjustable-Rate Mortgage (ARM)
To truly appreciate the stability of a fixed rate, it helps to compare it to its primary alternative: the adjustable-rate mortgage (ARM).
An ARM typically starts with a lower interest rate during an initial “introductory period” (usually 3, 5, 7, or 10 years). Once this period ends, however, the rate adjusts at regular intervals based on a market index (such as the Secured Overnight Financing Rate, or SOFR) plus a predetermined margin set by the lender.
To protect borrowers from extreme market swings, ARMs include rate caps that limit how much the rate can increase or decrease during a single adjustment period and over the lifetime of the loan. Even with these caps, your payments can rise significantly.
Historically, the gap between fixed and adjustable rates changes based on economic cycles. For example, back on August 13, 2020, the average interest rate nationwide on a 30-year fixed mortgage was 2.96%, while a comparable 5/1 ARM sat at 2.9%. The difference was a mere 0.06%. When the rate gap is that narrow, choosing a fixed rate is almost always the preferred choice because you get lifetime predictability for virtually the same price.
| Feature | Fixed-Rate Mortgage | Adjustable-Rate Mortgage (ARM) |
|---|---|---|
| Interest Rate | Permanent; never changes | Variable; changes after introductory period |
| Monthly Payment | Highly predictable | Can rise or fall over time |
| Initial Rate | Typically slightly higher | Often lower during the initial period |
| Best For… | Long-term homeowners, budget-conscious buyers | Short-term homeowners, buyers expecting rates to fall |
| Complexity | Simple and straightforward | Higher; requires understanding indexes, margins, and caps |
For a deeper dive into how stable payments keep your household budget secure, check out this guide on Understanding Fixed-Rate Payments: How They Work with Examples.
How Amortization Works on a Fixed Rate Mortgage
If your monthly payment never changes, how does your loan actually get paid off? The answer lies in a process called amortization.
When you first start paying off your mortgage, the vast majority of your monthly payment goes toward paying off interest, while only a small sliver goes toward reducing your principal balance. Month by month, this ratio gradually shifts. As your outstanding principal balance decreases, the amount of interest generated each month drops. Consequently, a larger portion of your fixed payment is directed toward the principal.
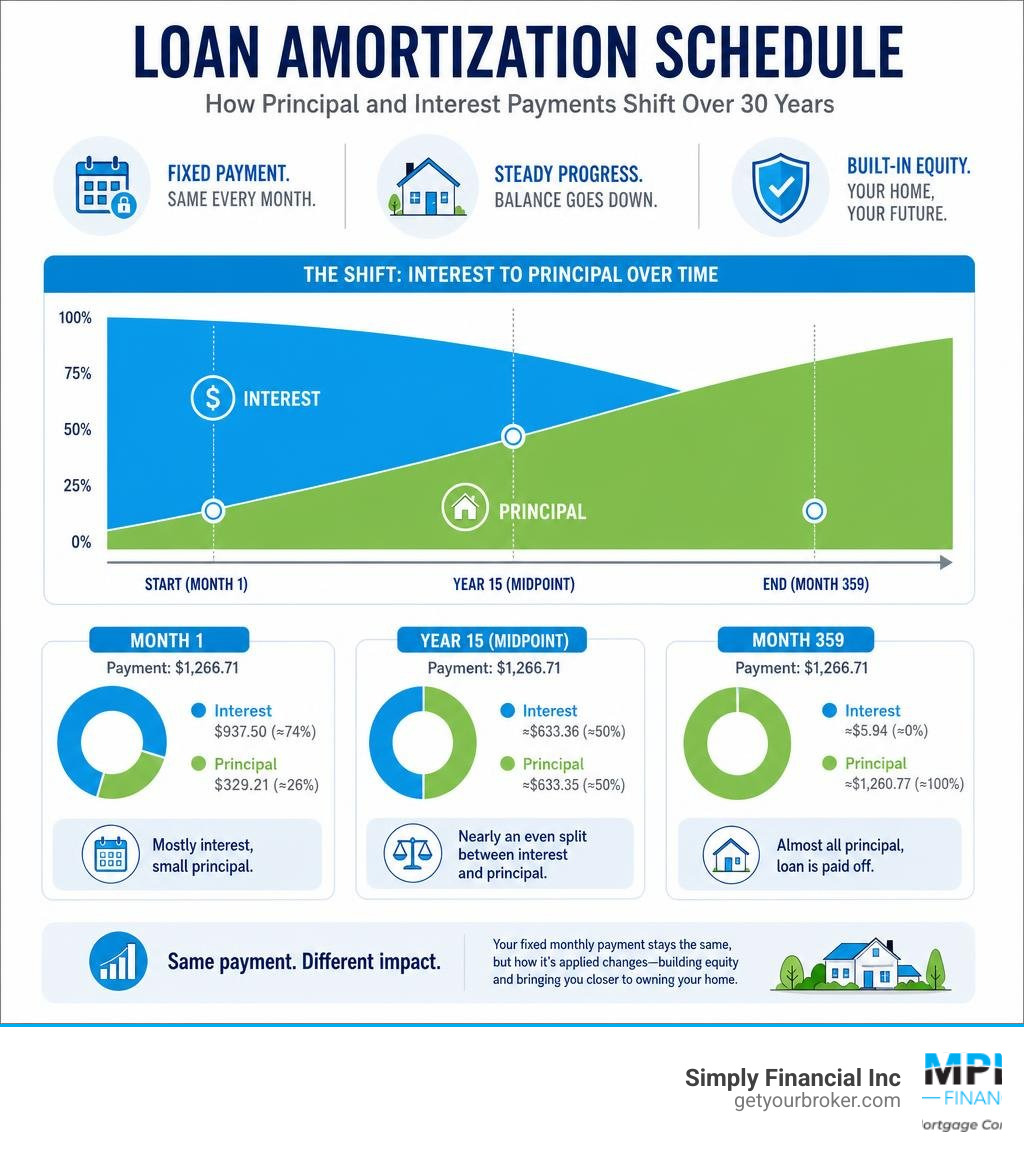
For example, on a $250,000, 30-year fixed-rate mortgage at a 4.5% interest rate, your monthly principal and interest payment is exactly $1,266.71.
- In Month 1, about $937.50 of that payment goes straight to interest, and only $329.21 goes to principal.
- By Year 15, the split is nearly equal.
- By Month 359, almost the entire $1,266.71 goes toward your principal, wiping out the remaining balance.
Because we believe in making home financing transparent, we recommend exploring our comprehensive guide on Mortgage Loan Options to see how different structures align with your personal financial goals.
Current Market Rates and How They Are Determined
When you look at daily mortgage rates, you might wonder where those numbers come from. The primary benchmark for national mortgage rates is Freddie Mac’s Primary Mortgage Market Survey (PMMS).
Historically, Freddie Mac surveyed lenders weekly to compile this data. However, in November 2022, the methodology evolved. Today, Freddie Mac calculates national averages using actual loan application data submitted to its Loan Product Advisor (LPA) platform. This data represents thousands of real applications from credit unions, commercial banks, and independent mortgage companies across the country, focusing on conventional, single-family home loans with an 80% loan-to-value (LTV) ratio.
Interestingly, Freddie Mac discontinued publishing ARM rates and upfront fees/points because fixed-rate products so heavily dominate the modern borrower profile.
Understanding 30-Year and 15-Year Fixed-Rate Averages in June 2026
As of June 18, 2026, the mortgage market has shown signs of cooling compared to the higher rates seen in previous years:
- The 30-year fixed-rate mortgage averaged 6.47%, down from 6.52% the previous week and 6.81% in June 2025.
- The 15-year fixed-rate mortgage averaged 5.81%, compared to 5.84% the prior week and 5.96% a year ago.
While national averages provide a great baseline, mortgage rates are highly regional. If you are shopping for a home in our primary service areas, you will see slight variations. For instance, around mid-June 2026, the average rate for a 30-year fixed mortgage in New York was 6.58%, with the 15-year fixed at 6.02%.
For local, up-to-the-minute pricing in our active markets, you can review the latest data directly:
- If you are buying in the Midwest, check out the Illinois mortgage and refinance rates for June 2026 – Bankrate.
- If you are purchasing in the Sunshine State, keep an eye on the Florida Mortgage and Refinance Rates for June 2026 – Bankrate.
Key Factors That Influence Mortgage Rates Over Time
Mortgage rates do not move in a vacuum. They are influenced by a complex web of economic indicators:
- The 10-Year Treasury Yield: Mortgage rates track the 10-year U.S. Treasury bond yield very closely. When bond yields rise, mortgage rates almost always follow.
- Inflation: Inflation is the arch-nemesis of fixed-income assets. When inflation is high, the purchasing power of future mortgage payments drops, causing investors to demand higher interest rates to offset the risk.
- Federal Reserve Policy: While the Fed does not set mortgage rates directly, its decisions regarding the federal funds rate and its balance sheet of mortgage-backed securities (MBS) heavily influence overall borrowing costs.
- Economic Growth: Strong economic reports (like high GDP growth and low unemployment) tend to push mortgage rates higher, while signs of an economic slowdown or recession typically pull rates downward.
Comparing Loan Terms and Options
Choosing a fixed rate mortgage is only your first decision. Next, you need to decide how long you want to take to pay it off.

15-Year vs. 30-Year Terms: Payments and Total Interest
The battle between the 15-year and the 30-year mortgage comes down to a simple trade-off: monthly affordability vs. lifetime interest savings.
- The 30-Year Fixed: This is the most popular choice because it spreads your payments over three decades, keeping your monthly obligation low and giving you maximum breathing room in your budget. The downside? You will pay significantly more in total interest over the life of the loan.
- The 15-Year Fixed: This term typically offers a lower interest rate than its 30-year counterpart. However, because you are compressing the repayment timeline into 15 years, your monthly payments will be much higher. The massive upside is that you build equity twice as fast and save tens of thousands of dollars in interest.
To see this in action, let’s compare a $300,000 home loan at June 2026 average rates:
- 30-Year Fixed at 6.47%: Your monthly principal and interest payment would be approximately $1,890. Over 30 years, you would pay a staggering $380,400 in total interest.
- 15-Year Fixed at 5.81%: Your monthly payment jumps to approximately $2,501 (an extra $611 per month). However, you would only pay $150,180 in total interest over the life of the loan—saving you over $230,000!
Buying Down Your Rate with Mortgage Points
If you want to secure a lower rate than the current market average, you can choose to buy mortgage points (also known as discount points) at closing.
One mortgage point costs exactly 1% of your total loan amount. In exchange for this upfront payment, the lender will typically lower your interest rate by 0.25%.
Paying points makes the most sense if you plan to stay in the home long enough to reach your “break-even point.” To calculate this, divide the upfront cost of the points by the amount you save on your monthly payment. For example, if paying $3,000 upfront saves you $50 a month, your break-even point is 60 months (5 years). If you plan to keep the loan for 7 or 10 years, buying points is a smart financial move. If you plan to sell or refinance in 3 years, you should skip the points and keep your cash upfront.
When you are ready to explore your options, you can work with a trusted mortgage broker to see how different point structures affect your bottom line.
Qualifying for a Fixed-Rate Home Loan
Qualifying for a conventional fixed rate mortgage requires meeting standard financial benchmarks. While we guide you through every step of this process to make it as stress-free as possible, knowing what lenders look for is key.
Conventional Loan Requirements: Credit, Down Payment, and DTI
To qualify for a conventional fixed-rate loan, lenders typically evaluate three main criteria:
- Credit Score: You generally need a minimum credit score of 620 to qualify for a conventional loan. However, to secure the most competitive interest rates, lenders look for a score of 740 or higher.
- Down Payment: While a 20% down payment is ideal because it allows you to avoid paying Private Mortgage Insurance (PMI), many conventional programs allow down payments as low as 3% for qualified buyers.
- Debt-to-Income (DTI) Ratio: Your DTI is the percentage of your gross monthly income that goes toward paying debts (including your future mortgage payment). Conventional guidelines typically require a DTI of 43% or less, though some strong profiles can go higher.
To take the first step toward finding your budget, check out our Pre-Qualify Chicago Mortgage Pre-Approval portal.
Government-Backed Fixed-Rate Loans: FHA, VA, and USDA
If a conventional loan does not fit your financial profile, several government-backed fixed-rate options offer more flexible guidelines:
- FHA Loans: Backed by the Federal Housing Administration, these loans are perfect for buyers with lower credit scores. You can qualify with a credit score as low as 580 with a modest 3.5% down payment.
- VA Loans: Backed by the Department of Veterans Affairs, these loans offer incredible benefits for active military members, veterans, and surviving spouses, including 0% down payment options, no monthly mortgage insurance, and highly competitive rates.
- USDA Loans: Backed by the U.S. Department of Agriculture, these loans offer 0% down financing for low-to-moderate-income buyers purchasing homes in designated rural areas.
Ready to see which program fits your needs? Fill out our quick Pre-Qualify Form to get started.
First-Time Homebuyer Programs and Down Payment Assistance
If you are buying a home in Illinois or Florida, there are numerous local down payment assistance (DPA) programs designed to help you bridge the gap.
In Illinois, programs through the Illinois Housing Development Authority (IHDA) can provide thousands of dollars in forgivable grants or zero-interest loans to cover your down payment and closing costs. Florida offers similar programs, such as the Hometown Heroes housing program, which helps essential workers secure low-interest down payment assistance. Most of these programs require you to take a brief homebuyer education course, which we highly recommend to help you feel confident throughout your journey.
Frequently Asked Questions about Fixed-Rate Mortgages
Can I lock in a fixed rate mortgage?
Yes! A rate lock is an agreement between you and your lender that guarantees your interest rate will not change before closing, even if market rates rise. Rate locks typically last between 30 and 60 days. Some lenders also offer a “float-down” option, which allows you to grab a lower rate if market interest rates drop significantly while your loan is in underwriting.
What happens when a fixed-rate mortgage term ends?
In the United States, standard fixed-rate mortgages are fully amortizing. This means that when your term ends (for example, after making your 360th payment on a 30-year loan), your balance is exactly $0 and you own your home free and clear. This is different from some international markets—such as the UK, where fixed rates typically only last for 2 to 5 years before reverting to a variable rate, requiring you to refinance or face higher payments.
Can I pay off my fixed-rate mortgage early?
Absolutely. Most modern conventional and government-backed fixed-rate mortgages do not carry prepayment penalties. You can make extra principal payments whenever you like, which will shorten your loan term and save you money on interest over time.
Conclusion
Navigating the mortgage market does not have to be overwhelming. At Simply Financial Inc, we specialize in delivering a seamless, expert-guided, and completely stress-free mortgage experience. Whether you are searching for a conventional home loan, exploring government-backed options, or trying to secure a competitive Fixed Rate Mortgage Chicago, our team is here to guide you home.
While you can research national options, working with a dedicated brokerage like Simply Financial Inc ensures you receive personalized, local support tailored specifically to the Illinois and Florida markets.
Come visit us at our Chicago office located at 5632 W Lawrence Ave Chicago IL, or reach out online today. Let’s make your homeownership dreams a reality—predictably, securely, and without the stress. Contact Us Chicago Mortgage Lender today to get started!