

Why Illinois First-Time Homebuyers Have More Help Than Ever in 2026
If you’re an Illinois first time homebuyer, here’s what you need to know upfront:
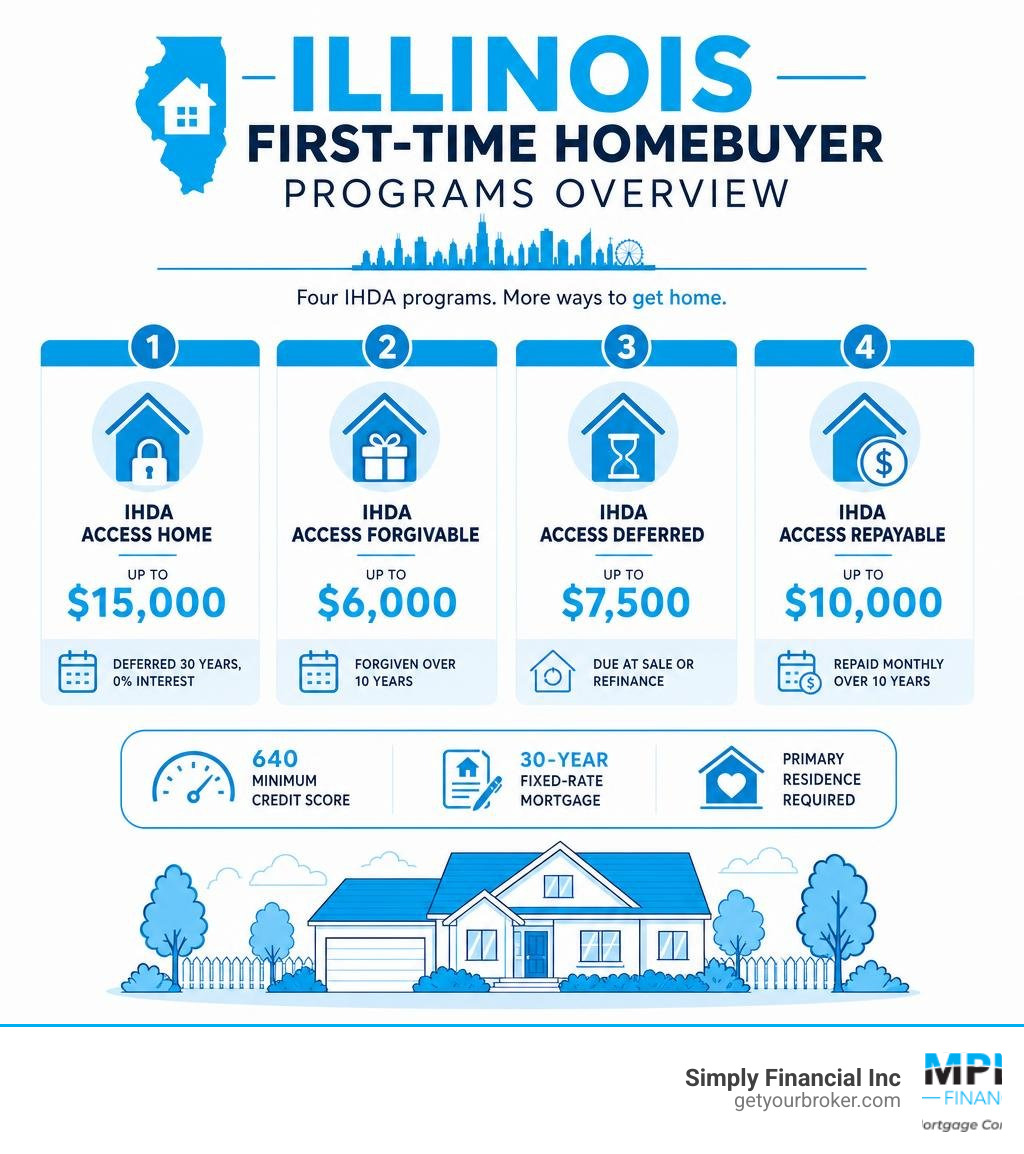
Top Illinois first-time homebuyer programs at a glance:
| Program | Assistance Amount | Repayment |
|---|---|---|
| IHDA Access Home | Up to $15,000 | Deferred 30 years, 0% interest |
| IHDA Access Forgivable | Up to $6,000 | Forgiven over 10 years |
| IHDA Access Deferred | Up to $7,500 | Due at sale or refinance |
| IHDA Access Repayable | Up to $10,000 | Repaid monthly over 10 years |
All four programs require a 640 minimum credit score, a 30-year fixed-rate mortgage, and the home must be your primary residence.
Buying your first home in Illinois feels expensive before you even start. The down payment alone can stop a lot of people in their tracks.
But here’s the thing — Illinois has some of the most active homebuyer assistance programs in the country. The Illinois Housing Development Authority (IHDA) has helped more than 34,000 Illinoisans buy homes over the past five years. And first-time buyers make up a striking 87% of IHDA borrowers, compared to just 21% nationally.
The newest program, Access Home, launched in March 2026 and became IHDA’s most popular option almost immediately — within nine weeks, more than 1,500 buyers had been offered upwards of $18 million in down payment help.
This guide breaks down every major program available to you right now, who qualifies, how to apply, and how to stack programs to maximize your assistance.
The IHDA Access Programs: Your Guide to Illinois First Time Homebuyer Assistance
The Illinois Housing Development Authority (IHDA) is the heavy hitter when it comes to state-level down payment assistance (DPA). IHDA doesn’t lend money directly to you. Instead, they partner with approved mortgage lenders like us to offer affordable, 30-year fixed-rate mortgages paired with second mortgages that cover your down payment and closing costs.
No matter which IHDA program you choose, you must contribute either $1,000 or 1% of the purchase price (whichever is greater) from your own funds. The property must also serve as your primary residence. Beyond those shared rules, the programs differ significantly in how much help they offer and how you pay it back.
Access Home: The Premier Option for an Illinois First Time Homebuyer
If you qualify, the Access Home program is usually the best deal on the table. Launched by the state in early 2026, this program was designed to offset the rising home prices across Illinois.
Access Home provides a massive boost: 6% of the purchase price up to a maximum of $15,000 in down payment and closing cost assistance. This money is structured as a zero-interest, silent second mortgage.
What makes it “silent”? You do not make monthly payments on this assistance. The repayment is completely deferred for the 30-year life of your first mortgage. You only pay it back when you sell the home, refinance your mortgage, or pay off the first loan.
According to state reports, More than 1,500 first-time homebuyers benefit from state’s ‘Access Home’ program within the first nine weeks of its launch, representing 61% of all IHDA loan reservations in 2026. The Pritzker administration launches new down payment assistance program to lower barriers for working families, and it has quickly become the state’s flagship housing initiative.
For a deeper dive into low-down-payment strategies, you can read our guide on Low Down Payment Mortgage Chicago.
Access Forgivable, Deferred, and Repayable Programs
If you don’t use Access Home, or if you are a repeat homebuyer looking for assistance, IHDA offers three other distinct programs under the “Access” umbrella. You can explore these options in detail in our review of First Time Home Buyer Programs Chicago.
- Access Forgivable: This program offers up to 4% of the purchase price (capped at $6,000). The best part? You don’t have to pay it back if you stay in the home. The loan is forgiven monthly over a 10-year period (120 months). If you sell or refinance before those 10 years are up, you only owe the remaining unforgiven balance.
- Access Deferred: This option provides up to 5% of the purchase price (capped at $7,500). Like Access Home, there are no monthly payments, and the loan is interest-free. The entire balance is deferred and becomes due only when you sell, refinance, or pay off your primary mortgage.
- Access Repayable: If you need a larger percentage of assistance, Access Repayable provides up to 10% of the purchase price (capped at $10,000). However, this is not deferred or forgiven. You must repay this interest-free second mortgage monthly over a 10-year period, which will add a small amount to your overall monthly housing payment.
Eligibility Requirements for Illinois Homebuyers
Securing free or deferred money sounds amazing, but you have to clear several hurdles to qualify. IHDA programs have strict guidelines regarding credit, household income, and the price of the home you want to buy.

Credit Score and Financial Requirements for an Illinois First Time Homebuyer
To qualify for any of the four IHDA Access programs, you must have a minimum credit score of 640. This requirement applies to all borrowers on the loan. If your score is slightly below this window, don’t worry—it’s a great opportunity to learn How to Establish First Time Credit and boost your score over a few months.
Lenders will also review your debt-to-income (DTI) ratio and overall credit profile. While some programs allow for flexible financing, these are not automatically 100% Financing Home Loans First Time Buyer. You will still need to show stable employment and document your assets to prove you can handle the monthly payments.
County Income and Purchase Price Limits
Because these programs are designed to help lower- and moderate-income households, IHDA sets limits on how much money your household can earn and how much the home can cost. These limits vary significantly depending on the county and whether the property is in a “targeted” or “non-targeted” area.
Targeted areas are federally designated neighborhoods where the government wants to encourage homeownership. In targeted areas, first-time buyer requirements are waived, and income and purchase limits are much higher.
Here is a look at the non-targeted limits for key Illinois counties in 2026:
- Cook County (and collar counties like DuPage, Lake, and Will):
- Income Limit (1-2 person household): $119,900
- Income Limit (3+ person household): $137,885
- Purchase Price Limit (1-Unit home): $544,232
- Sangamon County (Springfield area):
- Income Limit (1-2 person household): $114,700
- Income Limit (3+ person household): $131,905
- Madison County (Metro East area):
- Income Limit (1-2 person household): $111,400
- Income Limit (3+ person household): $128,110
- Winnebago County (Rockford area):
- Income Limit (1-2 person household): $110,100
- Income Limit (3+ person household): $126,615
To ensure compliance, lenders use automated compliance checks to verify your household size, income, and the exact address of the property against current IHDA limits.
How to Apply: The Step-by-Step IHDA Loan Process
Navigating the mortgage process can feel overwhelming, but breaking it down into simple steps keeps it manageable and stress-free.

Finding an Approved Lender and Getting Pre-Approved
Your first step is to connect with an IHDA-approved mortgage lender. Because IHDA does not originate loans directly, you must work with a participating institution that can register your loan with the state.
During your initial consultation, we will pull your credit, verify your income, and issue a pre-approval letter. This letter tells real estate agents that you are a serious buyer with the financial backing to make an offer. To get started on this step, you can complete our quick online Pre-Qualify Form or read more about the process in our guide to Pre-Qualify Chicago Mortgage Pre-Approval.
Completing Homebuyer Education and Closing
Once you find a home and your offer is accepted, your lender will lock in your interest rate and reserve your IHDA down payment funds.
Before your loan can officially close, you must complete a certified pre-purchase homebuyer education course. This is a mandatory 6-to-8-hour class (available online or in-person through approved housing counseling agencies) that teaches you the basics of home maintenance, budgeting, and mortgage management.
Once you complete the class, submit your certificate to your loan officer. From there, the underwriter will perform final checks, and you’ll head to the closing table to sign your paperwork and collect your keys!
Pairing IHDA with FHA, VA, USDA, and Conventional Loans
One of the best features of IHDA down payment assistance is its flexibility. It doesn’t replace your standard mortgage; instead, it rides shotgun. You can pair IHDA second mortgages with several types of first mortgages.
Government-Backed Loans and IHDA Assistance
Many buyers choose to pair IHDA assistance with a government-backed first mortgage:
- FHA Loans: Pairing IHDA with an FHA loan is incredibly popular. FHA loans have flexible credit guidelines and allow for a lower down payment. By adding IHDA assistance, you can easily cover the 3.5% down payment requirement and use the remaining funds for closing costs. Read more about this option in our guide to the FHA Loan Chicago.
- VA Loans: If you are an eligible veteran or active-duty service member, you can pair IHDA with a VA loan. Since VA loans already offer 100% financing, you can use the IHDA funds entirely to cover your closing costs, leaving you with virtually zero out-of-pocket expenses.
- USDA Loans: For buyers purchasing homes in designated rural areas, USDA loans offer 100% financing. Pairing this with IHDA assistance can help cover closing costs and prepaid items like property taxes and insurance.
Conventional HFA Loans vs. Government Options
If you have stronger credit, pairing IHDA with a conventional loan might be your best bet. Programs like Fannie Mae HFA Preferred and Freddie Mac HFA Advantage are conventional mortgages designed specifically for housing finance agencies.
Unlike standard conventional loans, these HFA conventional options offer reduced private mortgage insurance (PMI) rates, which can save you a significant amount of money on your monthly payment. They also bypass some of the strict property standards associated with FHA loans, making the closing process smoother.
Local Down Payment Assistance and Tax-Advantaged Savings in Illinois
While state-level IHDA programs are fantastic, they aren’t the only game in town. Depending on where you are looking to buy, you may be able to access local grants or tax incentives.
City of Chicago and County-Level Programs
Several municipalities in Illinois manage their own local homebuyer programs:
- Madison County HOMEbuyer Program: This local county program assists low-to-moderate-income buyers by providing up to $15,000 for down payments and closing costs. It requires a minimum median credit score of 620, and your household income must not exceed 80% of the area median income (AMI).
- Chicago Housing Authority (CHA) DPA: The CHA offers dedicated Down Payment Assistance to help families transition from renting to owning.
- City of Chicago Department of Housing: The city frequently runs localized programs for buyers purchasing within city limits. You can explore current options on the City of Chicago page For Homebuyers – City of Chicago.
- Habitat for Humanity Chicago: For those looking for affordable, community-driven homeownership models, the AFFORDABLE HOMEOWNERSHIP PROGRAM OVERVIEW provides excellent resources and pathways.
Illinois Home Buyer Savings Accounts Act and Finally Home Program
If you are planning ahead, the state of Illinois offers unique financial tools to help you save and secure a mortgage:
- Illinois Home Buyer Savings Accounts Act (SB0148): This state law allows first-time and “second-chance” buyers (those who haven’t owned a home in the last 10 years) to open tax-advantaged savings accounts. Individual filers can deduct up to $5,000 annually (joint filers up to $10,000) from their state taxable income for contributions made to these accounts. Earnings on the account are also exempt from state taxes, helping your down payment fund grow faster. You can review the legislative details at SB0148 104TH GENERAL ASSEMBLY.
- Finally Home Program: Managed by the Illinois State Treasurer, this program provides a five-year, 10% mortgage loan guarantee to participating lenders. It is designed to help lower-to-middle-income families who fall just short of standard underwriting guidelines due to bruised credit or high DTI ratios. Learn more about this credit enhancement tool at the Lower- to Middle-Income Families Refinance Guide – Illinois State Treasurer.
Frequently Asked Questions About Illinois First-Time Homebuyer Programs
What is the minimum credit score required for IHDA programs?
The minimum credit score required for all four IHDA Access programs is 640. If your score is below 640, you will not qualify for IHDA assistance, but you may still qualify for other non-IHDA loan options or local programs (like the Madison County program, which accepts a 620 score). Working on credit repair for 60 to 90 days is often the best path forward if you are close to the limit.
Do I have to repay the down payment assistance from IHDA?
It depends on the program you choose:
- Access Home & Access Deferred: Repayment is deferred. You do not make monthly payments, but you must repay the balance when you sell, refinance, or pay off your primary mortgage.
- Access Forgivable: The loan is forgiven monthly over 10 years. If you stay in the home for 10 years, you owe nothing.
- Access Repayable: You must repay the assistance monthly over a 10-year term.
Can I combine IHDA assistance with other local grants?
Yes, in many cases you can “stack” IHDA assistance with municipal or county-level grants, provided both programs allow it and your lender’s underwriting guidelines approve the combination. Stacking programs is a highly effective way to minimize your out-of-pocket costs at closing.
Conclusion
Navigating grants, silent second mortgages, and tax-advantaged savings accounts can feel like learning a second language. But you don’t have to figure it out alone.
At Simply Financial Inc, we are dedicated to delivering a seamless, expert-guided, and stress-free mortgage experience. Whether you want to apply for the popular Access Home program or compare conventional loans with government-backed options, our team is here to help you make the right move.
Ready to take the first step toward owning your home? Visit our Simply Financial Chicago Low Down Payment Guide to explore your options and connect with an expert today!