

What You Need to Know Before Taking Out an Investment Property Loan
An investment property loan is a mortgage used to buy real estate you plan to rent out or sell for profit — not to live in yourself. It works differently from a standard home loan, and the requirements are stricter.
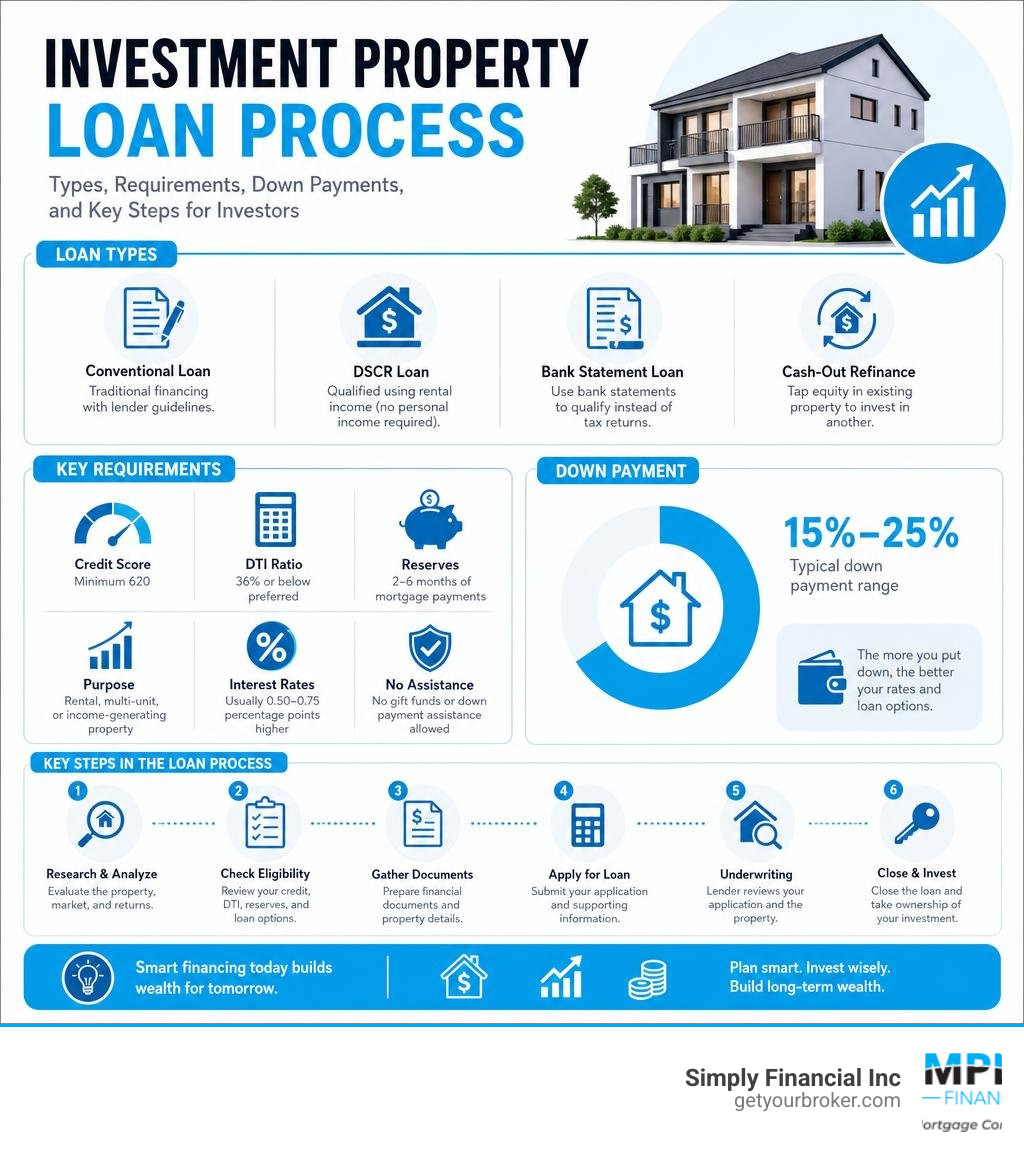
Here’s a quick summary of what to expect:
- Purpose: Finance a rental, multi-unit, or income-generating property
- Down payment: Typically 15%–25% (no gift funds or down payment assistance allowed)
- Credit score: Minimum 620, but 720+ gets you the best rates
- Interest rates: Usually 0.50–0.75 percentage points higher than primary residence loans
- Key loan types: Conventional, DSCR, bank statement, cash-out refinance
- DTI ratio: Lenders prefer 36% or below
- Reserves: Most lenders want 2–6 months of mortgage payments in savings
Real estate has historically been a solid investment — but it’s not risk-free. Experts generally note that it can take up to seven years before your upfront mortgage costs start to pay off. That’s a long runway, and knowing your financing options from the start can make a big difference.
This guide breaks down every major loan type, qualification requirement, and cost to help you choose the right path — whether you’re buying your first rental or growing a portfolio.
What is an Investment Property Loan?
To understand an investment property loan, you have to look at it through the eyes of a lender. When you buy a primary residence, you are highly motivated to make your mortgage payments because, well, you live there. If times get tough, you will do whatever it takes to keep a roof over your head.
With a rental property, the risk dynamic changes. If you face a financial pinch, you are far more likely to default on an investment property than on your own home. Because of this higher risk, lenders do not treat investment properties the same way they treat primary residences.
This difference in risk translates directly into how these loans are structured:
- Occupancy Requirements: You must certify that you do not intend to occupy the property. If you say you are going to live there just to get a lower rate but immediately rent it out, that is considered mortgage fraud.
- Higher Interest Rates: To compensate for the added risk, interest rates on an investment property loan typically run 0.50 to 0.75 percentage points higher than primary residence rates.
- Stricter Qualification: You will face higher down payment requirements, stricter debt-to-income (DTI) limits, and larger cash reserve demands.
Additionally, as we mentioned earlier, it takes as many as seven years before the upfront costs of purchasing and financing a rental property are fully defrayed. Real estate investing is a long-term game. If you plan to sell the property quickly, traditional long-term financing might not be your best option.
Before you dive in, it is vital to review all your Mortgage Loan Options to ensure your financing strategy aligns with your long-term wealth goals.
Types of Financing for Rental Properties
As you build your real estate portfolio, you will quickly realize there is no one-size-fits-all loan. The right financing option depends on your financial profile, how you document your income, and the type of property you are buying.
Here is a side-by-side comparison of the three most common loan options for property investors:
| Feature | Conventional Loan | DSCR Loan | Bank Statement Loan |
|---|---|---|---|
| Primary Qualification | Personal income, tax returns, W-2s, and DTI | Property’s rental income (cash flow) | 12–24 months of personal or business bank deposits |
| Minimum Down Payment | 15% (20% to 25% preferred) | 20% to 25% | 20% |
| Minimum Credit Score | 620 (720+ for best rates) | 660 to 700 | 660 |
| Income Verification | Tax returns, pay stubs, W-2s | None (based on lease agreements/market rent) | Personal or business bank statements |
| Best For | Salaried buyers with strong personal income and low DTI | Self-employed or portfolio investors focused on property cash flow | Self-employed buyers with high revenue but high tax write-offs |
Choosing the right path is crucial for long-term portfolio growth. Let’s look closer at how these individual loan programs work.
Conventional Investment Property Loan Requirements
A conventional investment property loan is a mortgage that is not backed by a government agency (like the FHA, VA, or USDA). Instead, it conforms to guidelines set by Fannie Mae and Freddie Mac.
Because these loans conform to federal standards, they have strict conforming loan limits. In most parts of the country, the conforming loan limit for a one-unit property is around $832,750 (though this can be significantly higher in designated high-cost areas).
If you are looking at a conventional route, keep these factors in mind:
- Fixed-Rate Terms: You can choose from popular Fixed Rate Mortgage Chicago options, which offer stable, predictable monthly payments over 10, 15, 20, or 30 years.
- No Private Mortgage Insurance (PMI) Shortcuts: On a primary residence, you can put down less than 20% if you pay monthly PMI. For investment properties, while some conventional programs technically allow 15% down, lenders almost always require 20% to 25% down to secure competitive terms.
- Strict Personal Limits: Conventional guidelines limit individual investors to holding a maximum of 10 financed properties in their personal name. If you want to grow beyond this, you will need to transition to commercial or portfolio financing.
DSCR and Bank Statement Investment Property Loan Options
If you are self-employed, have a complex financial profile, or want to buy properties under an LLC, conventional loans can be a major headache. Fortunately, non-qualified mortgages (Non-QM loans) offer flexible alternatives.
Debt Service Coverage Ratio (DSCR) Loans
A DSCR loan is a game-changer for active real estate investors. Instead of looking at your tax returns, pay stubs, or personal debt-to-income ratio, the lender qualifies the loan based solely on the property’s ability to generate cash flow.
The lender calculates the DSCR by dividing the property’s gross monthly rental income by the monthly mortgage payment (which includes principal, interest, taxes, insurance, and HOA fees, also known as PITIA).
- A DSCR of 1.0x means the property’s rental income exactly matches its mortgage payment.
- A DSCR of 1.2x or higher is highly preferred, meaning the property generates 20% more income than its monthly debt obligations.
For detailed underwriting rules on these programs, you can review institutional guidelines like the DSCR Investor Solutions 3 program, which outlines how lenders evaluate cash-flow metrics.
Bank Statement Loans
For self-employed borrowers, write-offs are great at tax time but painful at mortgage time. If your tax returns show a low net income due to business deductions, a bank statement loan is an excellent alternative.
Instead of tax returns, lenders analyze 12 to 24 months of your personal or business bank statements. They look at your average monthly deposits to calculate a qualifying income, making it much easier for business owners and freelancers to qualify for an investment property loan.
Qualification Requirements and Underwriting Guidelines
Qualifying for an investment property loan is like running an obstacle course where the hurdles are just a little bit higher. Lenders want to see a rock-solid financial profile before they hand over the keys to an income property.

Here is what underwriting teams look at when reviewing your application:
Credit Score
While you can technically secure a conventional investment loan with a credit score of 620, doing so will cost you. Lenders adjust interest rates based on your credit score. To secure the most competitive interest rates and reasonable down payment requirements, you should aim for a score of 720 or higher.
Down Payment and Reserves
You cannot use down payment assistance programs, grants, or gift funds from family members to buy an investment property. Every dollar of your down payment must be verified as your own sourced capital.
In addition to the down payment, lenders require “reserves.” This is liquid cash (or easily accessible assets like stocks or retirement accounts) left over in your accounts after closing. Lenders typically demand 2 to 6 months of mortgage payments in reserves for the subject property, and they may require additional reserves for any other real estate assets you own.
Debt-to-Income (DTI) Ratio and Rental Income
For conventional loans, lenders prefer a DTI of 36% or lower, though some programs allow up to 45% with strong compensating factors.
To help you qualify, lenders will often let you use the projected rental income of the property you are buying to offset the new mortgage payment. Typically, they will count 75% of the projected gross rent (determined by a professional appraisal and market rent analysis) to account for potential vacancies and maintenance costs.
Borrower Experience
Are you a seasoned landlord or a first-time investor? Your track record matters. First-time investors are often subject to stricter guidelines, such as:
- A mandatory minimum credit score of 680 to 700.
- A requirement that you have owned your own primary residence for at least 12 months.
- Lower maximum loan-to-value (LTV) limits (meaning you have to put more money down).
If you want to keep your upfront costs as low as possible, it is worth exploring specialized regional programs like a Low Down Payment Mortgage Chicago to see if you qualify for creative financing structures.
Property Types and Geographic Considerations
Where you buy and what you buy will heavily influence your financing terms. Different property types carry different levels of risk, and local market regulations can impact your eligibility.

Multi-Unit Properties vs. Single-Family Homes
Financing a single-family home is relatively straightforward. However, if you are looking at multi-unit properties (2 to 4 units, like duplexes, triplexes, or fourplexes), the underwriting rules change.
- Down Payments: Multi-unit properties often require larger down payments (typically 25% down for conventional loans).
- House Hacking: If you plan to live in one of the units and rent out the others, you can qualify for primary residence financing (like FHA or conventional owner-occupied loans), which allows down payments as low as 3.5% to 5%.
Condominiums
Condos can be fantastic rental properties, but they come with an extra layer of underwriting. Lenders must approve the entire condo association, not just your individual unit.
- Warrantable vs. Non-Warrantable: A “warrantable” condo meets Fannie Mae and Freddie Mac guidelines (e.g., no single entity owns too many units, and the HOA has strong cash reserves). If a condo is “non-warrantable,” you cannot use a conventional loan and must use a Non-QM or commercial loan program.
- Florida Condo Rules: If you are investing in Florida, keep in mind that state regulations require strict structural integrity reserve studies for multi-story buildings. This has caused HOA fees and insurance costs to rise, which directly impacts your DSCR calculations.
Short-Term Rentals (STRs) vs. Long-Term Rentals
Are you planning to list the property on Airbnb or Vrbo, or do you want a traditional 12-month lease?
- Long-Term Rentals: Lenders love the predictability of long-term leases. Underwriters will easily accept standard lease agreements or a market rent study (Form 1007) to verify income.
- Short-Term Rentals: Because STR income fluctuates, lenders are more cautious. Some DSCR programs will allow you to use historical short-term rental data (using tools like AirDNA) to qualify, but they typically cap the maximum LTV at 75% and require higher credit scores.
If you are looking to purchase in the Midwest, check out our dedicated guide on Investment Property Loans in Chicago to understand local neighborhood trends, building codes, and municipal rules.
Refinancing, Costs, and Tax Implications
Buying the property is just the first step. Managing your equity, understanding your operational costs, and planning for taxes are what separate amateur landlords from professional real estate investors.
Refinancing Options: Cash-Out, HELOCs, and HELOANs
Once you have built up equity in an investment property, you can leverage it to fund your next acquisition.
- Cash-Out Refinance: This replaces your existing mortgage with a new, larger loan, allowing you to take the difference in cash. Lenders typically limit cash-out refinances on investment properties to 70% to 75% LTV, and they require you to have owned the property for at least 6 to 12 months (known as “seasoning”).
- HELOC (Home Equity Line of Credit): A variable-rate line of credit that lets you draw funds as needed. While common for primary residences, HELOCs on investment properties are harder to find and typically carry higher interest rates.
- HELOAN (Home Equity Loan): A second mortgage that provides a lump sum of cash at a fixed interest rate. This is a great option if you want to keep your low first-mortgage rate intact while accessing equity.
If you are dealing with high-value properties that exceed conforming limits, you may need to look into a Jumbo Loan Chicago to secure the large-scale capital required.
Holding Title in an LLC
Many experienced investors choose to hold their rental properties inside a Limited Liability Company (LLC). This protects your personal assets from lawsuits or property-related liabilities.
- Conventional loans do not allow you to close in the name of an LLC; you must close in your personal name and transfer the title later (which can trigger “due-on-sale” clauses if not handled carefully).
- DSCR and commercial loans actively encourage closing directly under an LLC, making them the preferred choice for serious portfolio builders.
Additional Costs and Tax Implications
Do not make the mistake of only budgeting for your mortgage payment. You must account for:
- Property Management: Usually 8% to 12% of the monthly rent if you hire a professional.
- Maintenance and Capital Expenditures (CapEx): Set aside 10% to 15% of your monthly rental income for repairs (like a new roof or HVAC system).
- Taxes and Deductions: The good news is that real estate offers incredible tax benefits. You can write off mortgage interest, property taxes, insurance, maintenance, and even “depreciate” the physical building over 27.5 years to offset your rental income. Always consult a certified tax professional to maximize these benefits.
Frequently Asked Questions about Investment Property Financing
What is the typical down payment for an investment property?
While primary residences can be purchased with as little as 3% to 5% down, investment properties require a much larger financial commitment. The absolute minimum down payment is 15% for a conventional purchase of a single-family home, but most lenders require 20% to 25% down to secure competitive interest rates and avoid strict underwriting overlays. For multi-unit properties, expect a minimum of 25% down.
Can I use a DSCR loan if I am a first-time investor?
Yes! Many DSCR programs allow first-time investors to qualify. However, because you do not have a track record of managing rental properties, lenders will offset their risk by requiring:
- A minimum credit score of 680 to 700.
- Proof that you have owned and occupied a primary residence for at least the last 12 months.
- A slightly lower maximum loan-to-value (LTV) ratio, meaning you may need to put down 25% to 30% instead of the standard 20%.
How does a short-term rental affect my loan eligibility?
Short-term rentals (like vacation homes or Airbnb properties) are viewed as higher risk because their income is seasonal and less predictable than a standard 12-month lease. To qualify using short-term rental income, lenders will require a specialized appraisal that analyzes local vacation rental data. Additionally, most programs will cap your maximum LTV at 75% (requiring a 25% down payment) and will not allow you to qualify if the property’s calculated DSCR falls below 1.0x.
Conclusion
Navigating real estate investing requires more than just finding the perfect property — it requires securing the right financial foundation. Whether you are looking for a traditional conventional mortgage, a flexible DSCR loan, or a specialized bank statement program, matching your financing to your investment strategy is the key to building long-term wealth.
At Simply Financial Inc, we believe that financing your next rental property should be a seamless, expert-guided, and stress-free experience. Our team of experienced mortgage professionals is licensed in Illinois and Florida, with our flagship office located right in the heart of Chicago, IL at 5632 W Lawrence Ave.
Ready to take the next step in your real estate journey? Explore your local options and connect with our team today by visiting our Investment Property Loans in Chicago portal. Let’s build your portfolio together!