

Why Low Down Payment Options Are Opening Doors for Today’s Homebuyers
For many buyers, low down payment options are the single most important factor standing between renting and owning a home. If you’re wondering what programs exist and whether you qualify, here’s a quick answer:
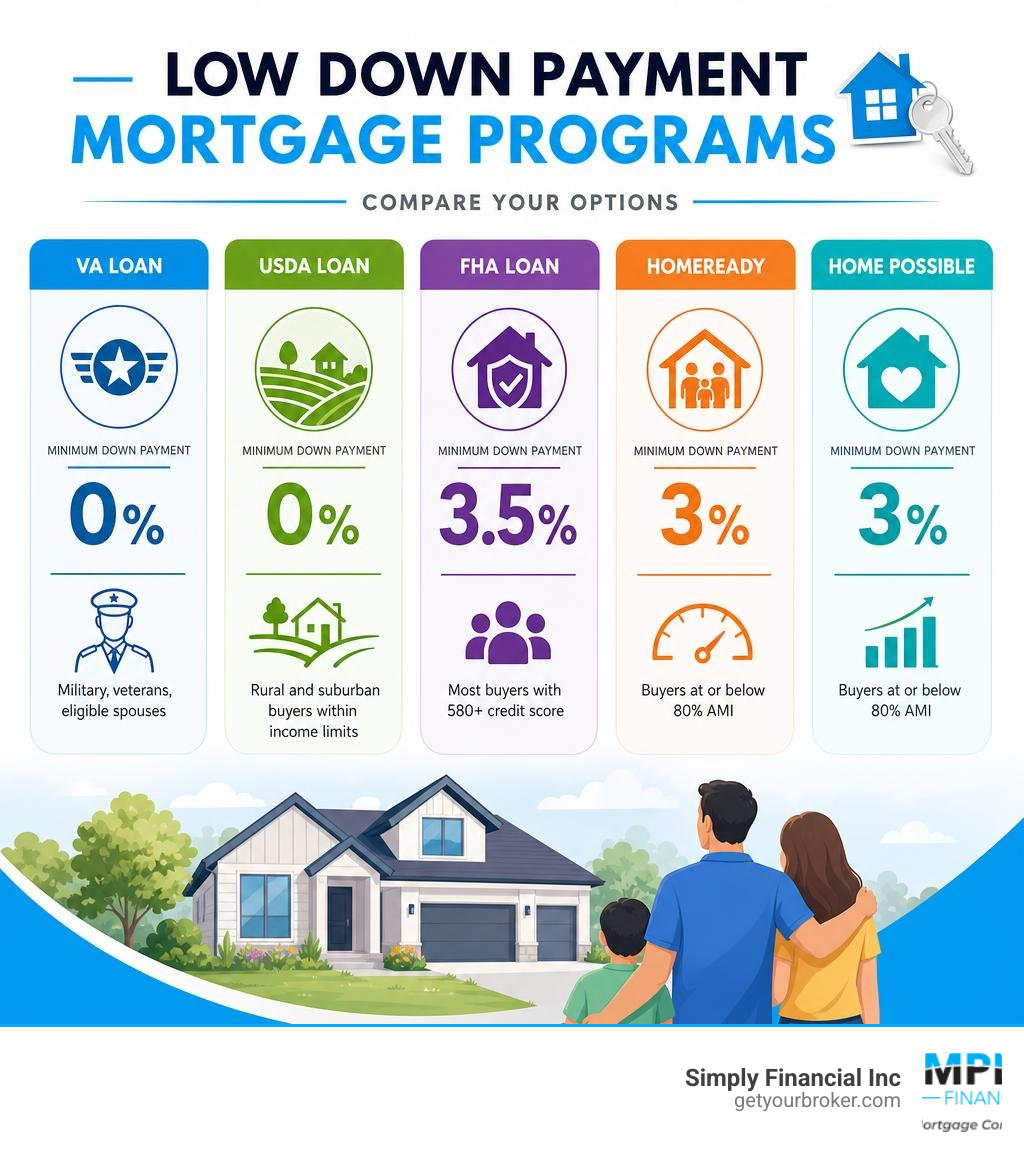
The most common low and no down payment mortgage options in 2026:
| Program | Minimum Down Payment | Who It’s For |
|---|---|---|
| VA Loan | 0% | Military, veterans, eligible spouses |
| USDA Loan | 0% | Rural and suburban buyers within income limits |
| FHA Loan | 3.5% | Most buyers with 580+ credit score |
| Fannie Mae HomeReady | 3% | Buyers at or below 80% AMI |
| Freddie Mac Home Possible | 3% | Buyers at or below 80% AMI |
Saving a full 20% down payment can take years — sometimes a decade or more in expensive markets. That’s a long time to wait, especially when rents keep climbing.
The numbers tell the story clearly. In 2025, the median down payment for first-time homebuyers hit 10% — the highest level in nearly four decades. That signals real pressure on buyers to come up with more cash upfront, even as home prices remain elevated.
But here’s what many buyers don’t realize: you don’t need anywhere near 20% to buy a home. Multiple programs let you get in the door with 3%, 1%, or even nothing down — each with different trade-offs around mortgage insurance, interest rates, and eligibility.
I’m Peter Babjak, a Chicago-based mortgage broker with over 18 years of experience helping first-time and repeat buyers navigate low down payment options to find the right fit for their financial situation. In this guide, I’ll walk you through every major program available so you can make a confident, informed decision.
Understanding Low Down Payment Options
When we talk about buying a home, the down payment is the upfront cash you pay toward the purchase price. The remaining balance is covered by your mortgage. For decades, a 20% down payment was considered the gold standard. However, in today’s dynamic real estate market, that standard is more of a myth than a rule.
To bridge the gap between high home prices and limited savings, modern lenders and government agencies offer a variety of low down payment options. These loans allow you to secure a mortgage with anywhere from 0% to 5% down.
When you purchase a property, you also need to account for closing costs—which typically range from 2% to 5% of the loan amount. These costs cover administrative fees, loan origination, appraisals, title searches, and prepayments for property taxes and home insurance. Fortunately, many low-down-payment programs allow you to pair your loan with grants, gifts, or seller concessions to minimize your out-of-pocket expenses.
If you are looking to purchase a property in the Chicagoland area, exploring a Low Down Payment Mortgage Chicago can help you keep your hard-earned savings intact while still achieving your dream of homeownership.
Why Buyers Seek Low Down Payment Options
The primary hurdle to buying a home is rarely the monthly mortgage payment; instead, it is the massive upfront cost of a traditional down payment. Saving tens of thousands of dollars while simultaneously paying high monthly rents can feel like running on a treadmill that keeps speeding up.
Consider this: the average federal tax refund in April was $3,275. While that is a helpful chunk of money, it represents only a small fraction of a traditional 20% down payment on an average home. However, when applied to low down payment options, that same tax refund could cover a substantial portion—or even the entirety—of your required down payment.
By choosing a low-down-payment route, first-time homebuyers can escape the rental cycle years ahead of schedule. This allows them to begin building long-term generational wealth through home equity and property appreciation, rather than pouring money into a landlord’s pocket.
Key Financial Metrics: LTV, CLTV, and Credit Scores
To qualify for any low-down-payment mortgage, you must understand three key metrics that underwriters use to evaluate your loan application:
- Loan-to-Value (LTV) Ratio: This measures the amount of your primary mortgage compared to the appraised value of the home. If you put 3% down, your LTV is 97%.
- Combined Loan-to-Value (CLTV) Ratio: This comes into play if you use secondary financing, such as a down payment assistance second mortgage. It measures the total of all loans secured by the property against its value. For example, some programs allow an LTV of 97% but a CLTV of up to 105% when secondary financing is used to cover closing costs.
- Credit Score and Debt-to-Income (DTI) Ratio: Your credit score determines your interest rate and your eligibility for specific programs. While government loans may accept credit scores as low as 580 (or even lower with larger down payments), conventional low-down-payment options typically require a minimum score of 620. Simultaneously, lenders look at your DTI—the percentage of your monthly gross income that goes toward paying debts—which generally needs to be under 43% to 50%, depending on the loan program.
Government-Backed No and Low Down Payment Mortgages
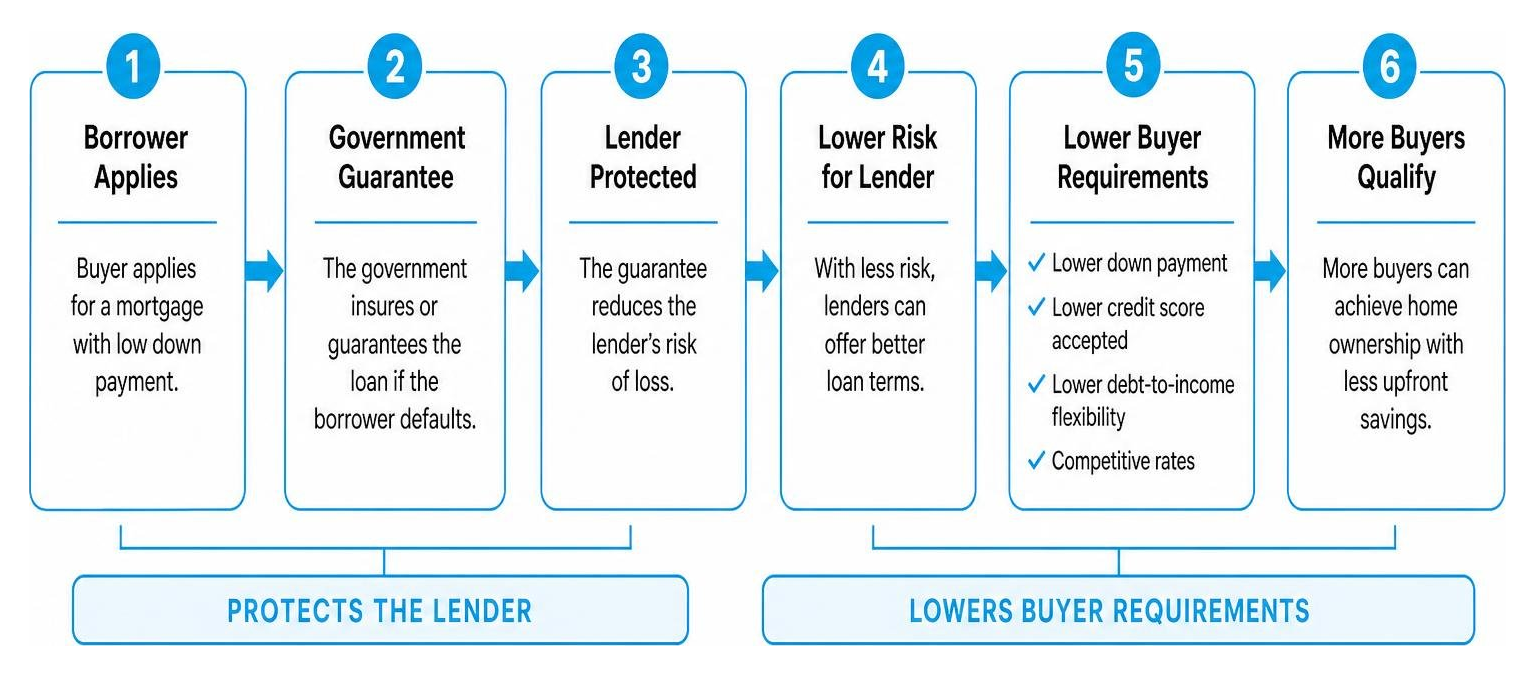
Government-backed loans are mortgages insured or guaranteed by federal agencies. Because the government agrees to protect the lender if the borrower defaults, lenders are willing to offer highly competitive rates and flexible credit guidelines.
These programs are excellent choices for buyers who may not have perfect credit or a massive savings account. However, they do come with additional costs, such as upfront and monthly mortgage insurance premiums (MIP) or government-mandated funding fees.
If you are a borrower in Illinois looking for flexible credit guidelines and low upfront costs, starting with an FHA Loan Chicago is one of the most reliable paths to homeownership.
FHA Loans: The 3.5% Down Standard
The Federal Housing Administration (FHA) loan program has been helping Americans buy homes since 1934. It remains one of the most popular options for first-time buyers due to its lenient credit requirements and low down payment barrier.
- Minimum Down Payment: 3.5% of the purchase price.
- Credit Score Requirement: You can qualify with a credit score as low as 580 with a 3.5% down payment. If your score is between 500 and 579, you may still qualify, but you will be required to put 10% down.
- Mortgage Insurance: FHA loans require both an Upfront Mortgage Insurance Premium (UFMIP)—typically 1.75% of the loan amount—and an annual Monthly Mortgage Insurance Premium (MIP) that lasts for the entire life of the loan if you put less than 10% down.
- Layering Assistance: FHA loans can be combined with state-specific programs like the 1st-home-illinois-down-payment-grant – FHA.com to help cover your down payment and closing costs.
VA Loans: 100% Financing for Military Families
For active-duty service members, veterans, and eligible surviving spouses, the VA home loan program is arguably the best mortgage product on the market. Backed by the U.S. Department of Veterans Affairs, it offers unmatched benefits for those who have served our country.
- Minimum Down Payment: 0% down payment required.
- No Monthly PMI: Unlike conventional and FHA loans, VA loans do not require monthly private mortgage insurance, which can save you hundreds of dollars every month.
- VA Funding Fee: To keep the program running, borrowers pay a one-time VA funding fee at closing, which ranges from 1.25% to 3.3% of the loan amount, depending on your down payment size and whether you have used the benefit before. This fee can be rolled into the total loan amount or waived entirely for veterans with service-connected disabilities.
- Affordable Path: If you qualify, you can read more about how to secure 100 Financing Home Loans First Time Buyer options to purchase your home with zero cash down.
USDA Loans: Zero Down for Rural Buyers
The United States Department of Agriculture (USDA) offers a Single Family Housing Guaranteed Loan Program designed to promote homeownership in rural and suburban communities.
- Minimum Down Payment: 0% down payment required.
- Geographic Restrictions: The property must be located in an eligible rural or suburban area as defined by the USDA. You might be surprised to learn that many outer suburbs of major metropolitan areas in Illinois and Florida qualify for this program.
- Income Limits: To qualify, your household income cannot exceed 115% of the area median income (AMI) for your county.
- Costs: USDA loans carry an upfront guarantee fee (usually 1% of the loan amount) and an annual fee (0.35% of the loan balance) paid monthly, which functions similarly to mortgage insurance but at a much lower rate than FHA loans.
Conventional Low Down Payment Programs
Conventional loans are mortgages that are not directly backed by a government agency. Instead, they follow guidelines set by the Government-Sponsored Enterprises (GSEs) Fannie Mae and Freddie Mac.
If you have solid credit, conventional low down payment options are often more appealing than FHA loans because private mortgage insurance (PMI) can be cancelled once you reach 20% equity in your home. To find out more about conventional 3% down programs, check out the resources at Unlock Homeownership with Just 3% Down – My Home by Freddie Mac .
Fannie Mae HomeReady: Flexible 3% Down
Fannie Mae’s HomeReady program is designed specifically for creditworthy, low-to-moderate-income borrowers.
- Minimum Down Payment: 3% down payment.
- Credit Score Requirement: Minimum credit score of 620.
- Income Constraints: Your household income must be at or below 80% of the Area Median Income (AMI) where the property is located.
- Unique Flexibilities: HomeReady allows you to use nontraditional income sources, such as boarder income or rental income from an accessory dwelling unit, to qualify. It also allows sweat equity (such as volunteer labor through a nonprofit housing provider) to count toward your down payment.
- Impact: Over 1.1 million Americans have purchased a home using this program. To learn more about how this program works, visit the official HomeReady Low Down Payment Mortgage | Fannie Mae page.
Freddie Mac Home Possible: Affordable 3% Down
Freddie Mac’s Home Possible program is another outstanding conventional option that mirrors HomeReady but offers its own set of underwriting flexibilities.
- Minimum Down Payment: 3% down payment.
- Credit Score Requirement: Minimum credit score of 620, though some borrowers may qualify without a traditional credit score under specific guidelines.
- Income Limit: Capped at 80% of the Area Median Income (AMI).
- Flexible Funding Sourced: Down payment and closing costs can come from a wide variety of sources, including family gifts, employer-assistance programs, housing grants, and sweat equity.
- Reduced PMI: Home Possible offers reduced private mortgage insurance premiums for loan-to-value ratios above 90%, helping to keep your monthly payments as low as possible. To explore this option further, see the Home Possible® – Freddie Mac Single-Family portal.
Proprietary 1% and Zero Down Conventional Loans
In addition to the standard GSE programs, many lenders offer specialized conventional products designed to lower the down payment barrier even further. For example, some lenders offer 1% down payment programs where the homebuyer contributes 1%, and the lender provides a non-repayable 2% grant (up to a maximum grant of $7,000) to reach the required 3% equity threshold. These programs are typically capped by income limits (80% AMI) and maximum loan amounts.
Other specialized products include zero-down conventional options that combine a first mortgage with a forgivable or silent second mortgage to cover the down payment, or non-conforming portfolio loans that waive monthly PMI entirely in exchange for a slightly higher interest rate.
Down Payment Assistance, Grants, and Creative Financing
If you don’t have enough savings to cover both your down payment and closing costs, you don’t have to wait. There are hundreds of down payment assistance (DPA) programs, grants, and creative financing structures designed to help you cross the finish line.
If you are looking to buy in the Chicago metropolitan area, you can explore the various First Time Home Buyer Programs Chicago that can be paired with your primary mortgage.
State and Local Down Payment Assistance Grants
Depending on where you live, state housing finance agencies and local municipalities offer incredibly generous programs to help buyers cover upfront costs.
- Illinois Housing Development Authority (IHDA): IHDA offers several loan and grant programs that provide thousands of dollars in assistance for down payments and closing costs. You can learn more about how to apply by visiting Getting An IHDA Loan .
- Florida Housing Finance Corporation: If you are buying in Florida, you can access down payment assistance programs, interest-free second mortgages, and closing cost grants through Homebuyer – Florida Housing Finance Corporation to help make homeownership more accessible.
- Chicago Housing Authority (CHA): CHA provides specialized grants for qualified buyers purchasing homes within the city limits. More details are available at Down Payment Assistance | Chicago Housing Authority .
- Federal Home Loan Bank of Chicago (FHLBC): The FHLBC offers the Downpayment Plus Program, providing matching grants for down payments and closing costs to eligible low-and-moderate-income homebuyers. Learn more at Downpayment Plus® Program – FHLBC .
Gift Funds and Seller Concessions
Another highly effective way to purchase a home with minimal cash out of pocket is through gift funds and seller concessions.
- Gift Funds: Most conventional and government loans allow family members, close friends, or employers to gift you the money needed for your down payment and closing costs. This requires a signed “gift letter” confirming that the funds are a gift and do not need to be repaid.
- Seller Concessions: You can negotiate with the seller to have them pay a portion of your closing costs. FHA and USDA loans allow sellers to contribute up to 6% of the purchase price toward closing costs, while conventional loans typically cap seller concessions at 3% for low-down-payment options.
Pros and Cons of Putting Less Money Down
Like any financial decision, choosing to use a low down payment option involves trade-offs. While it gets you into a home faster, it also means you will start with less equity and potentially face higher long-term costs.
To help you visualize the differences, here is a comparison of how different low-down-payment loan types stack up:
| Loan Type | Down Payment | PMI/MIP Required? | Credit Score | Best For |
|---|---|---|---|---|
| FHA | 3.5% | Yes (For life of loan) | 580+ | Lower credit scores |
| VA | 0% | No | Varies (often 580-620) | Military families |
| USDA | 0% | Yes (Low annual fee) | 640+ | Rural & suburban buyers |
| HomeReady | 3% | Yes (Can cancel at 20% equity) | 620+ | Low-income conventional buyers |
| Home Possible | 3% | Yes (Can cancel at 20% equity) | 620+ | Low-income conventional buyers |
The Benefits of Conserving Your Cash
The most obvious benefit of putting less money down is that it preserves your liquidity. Buying a home is expensive, and your expenses don’t stop once you get the keys. Keeping cash in your bank account gives you a robust emergency fund to handle unexpected home repairs, medical bills, or job transitions.
Conserving your cash also means you don’t have to wait years to buy. In a rising market, waiting five years to save a 20% down payment could mean paying significantly more for the exact same house later.
The Long-Term Costs of Low Down Payment Options
On the flip side, putting less money down means you are borrowing more. A larger loan balance translates directly into a higher monthly mortgage payment.
Furthermore, unless you are using a VA loan, you will have to pay mortgage insurance (PMI or MIP), which protects the lender against default. Conventional PMI can eventually be cancelled, but it still adds an extra monthly fee to your payment for the first several years of your loan. Finally, because you start with very little equity, you are more vulnerable to market fluctuations if home values dip.
Frequently Asked Questions About Low Down Payment Mortgages
Do I need a 20% down payment to buy a home in 2026?
Absolutely not! The idea that you must put 20% down to buy a home is a persistent myth. In fact, the median down payment for first-time homebuyers in 2025 was just 10%. With programs like HomeReady, Home Possible, and FHA loans, you can buy a home with as little as 3% to 3.5% down, and VA or USDA loans allow for 0% down.
Can I get a mortgage with 0% down if I am not in the military?
Yes. If you are not eligible for a VA loan, you can still get a 0% down mortgage through the USDA loan program, provided you purchase a home in an eligible rural or suburban area and meet the income guidelines. Additionally, you can look into state-specific first-time buyer grants to cover your down payment entirely. For residents of Illinois, exploring the Illinois First Time Homebuyer options can lead to local zero-down opportunities.
How do I remove private mortgage insurance (PMI) from my loan?
For conventional loans (like HomeReady or Home Possible), PMI is not permanent. Once your loan balance drops to 80% of your home’s original value—either through monthly payments or rising home values—you can request that your lender remove PMI. It drops off automatically at 78% LTV. For FHA loans, however, the monthly mortgage insurance premium (MIP) is permanent for the life of the loan if you put down less than 10%, meaning you would need to refinance into a conventional loan later to remove it.
Conclusion
Navigating low down payment options can feel overwhelming, but you don’t have to do it alone. At Simply Financial Inc, we specialize in providing home loans—including VA, FHA, USDA, and conventional options—tailored to your unique financial situation.
Our mission is simple: to deliver a seamless, expert-guided, and stress-free mortgage experience from your initial application all the way to closing day. Whether you are buying a home in Chicago or anywhere else in Illinois or Florida, we are here to help you find the perfect loan program.
Ready to take the first step toward your new home? You can easily Pre Qualify Chicago Mortgage Pre Approval online, or reach out to us directly to explore your customized Low Down Payment Mortgage Chicago options. Let’s make your dream of homeownership a reality!