

What You Need to Know About a USDA Loan in Walton County, FL
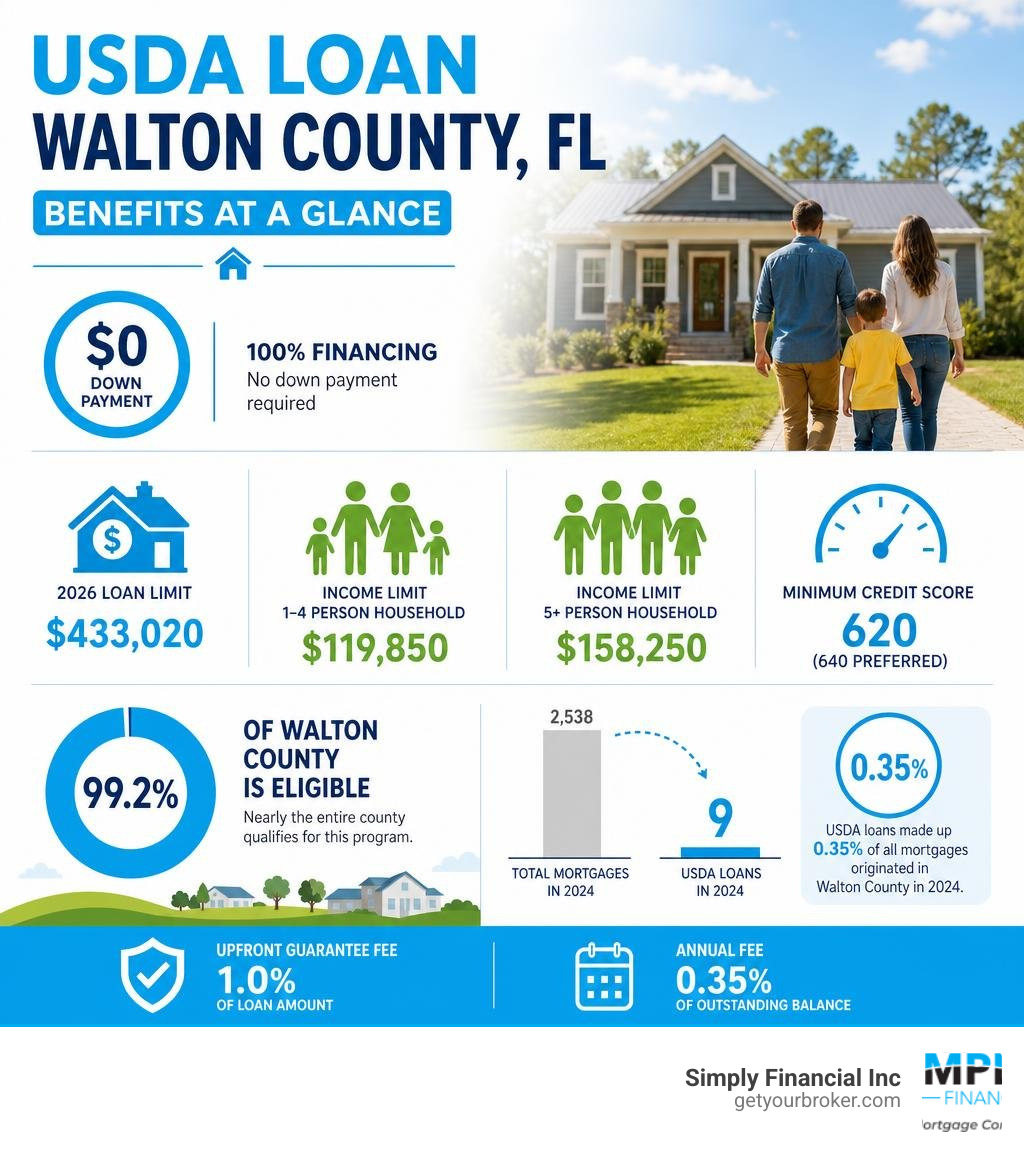
A USDA loan Walton County FL buyers can access is one of the last remaining zero-down-payment mortgage programs available to everyday homebuyers in 2026. If you’re looking to buy a home in Walton County without a large down payment, here’s the quick answer:
USDA Loan Walton County FL — Fast Facts for 2026:
| Feature | Details |
|---|---|
| Down payment required | $0 (100% financing) |
| 2026 loan limit | $433,020 |
| Income limit (1-4 person household) | $119,850 |
| Income limit (5+ person household) | $158,250 |
| Minimum credit score | 620 (640 preferred) |
| % of Walton County eligible | 99.2% |
| Upfront guarantee fee | 1.0% of loan amount |
| Annual fee | 0.35% of outstanding balance |
Nearly the entire county qualifies for this program — and most buyers are surprised to learn that popular Walton County communities like DeFuniak Springs, Freeport, and Paxton are all eligible.
Yet despite these advantages, USDA loans made up just 0.35% of all mortgages originated in Walton County in 2024 — only 9 loans out of 2,538 total. That means thousands of buyers who could have saved tens of thousands of dollars at closing likely chose a more expensive loan instead.
This guide walks you through everything you need to know: eligibility rules, income limits, how to check a specific address, and how to apply without the stress and confusion that usually comes with the mortgage process.
Understanding the USDA Loan Program in Florida
The United States Department of Agriculture (USDA) Rural Development program isn’t just for farmers. In fact, you don’t need to purchase a single tractor or grow a single ear of corn to qualify. The program was created to encourage homeownership in developing, suburban, and rural communities across Florida by offering 100% financing options to low-to-moderate-income families.
There are two primary paths under this program:
- Section 502 Direct Loan Program: This program assists low- and very-low-income applicants. It is funded directly by the government and offers payment assistance subsidies that can reduce the interest rate to as low as 1%. For very-low-income applicants, payback periods can even be extended up to 38 years. You can read the official parameters on the Single Family Housing Direct Home Loans in Florida page.
- Section 502 Guaranteed Loan Program: This is the most common path for moderate-income buyers. Private lenders (like us at Simply Financial Inc) issue the mortgage, while the USDA guarantees a portion of the loan against default. This backing allows us to offer you competitive interest rates with zero money down.
Both options make homeownership highly accessible, allowing you to bypass the biggest hurdle to buying a home: saving up a massive 5% to 20% down payment.
How to Qualify for a USDA Loan Walton County FL
To qualify for a USDA loan Walton County FL, both you and the property you want to buy must meet specific criteria. It is a dual-qualification process: your household finances must fit within the program’s limits, and the home must be located in a designated eligible area.
Beyond geography and income, you must:
- Occupy the property as your primary residence (no investment properties or vacation homes allowed).
- Be a U.S. citizen, non-citizen national, or qualified alien.
- Demonstrate a stable, dependable two-year history of income and employment.
- Have the legal capacity to incur a loan obligation.
For a closer look at local requirements, you can check out the Florida USDA Mortgage Loan -Bay Walton County resources.
Credit Score and Debt-to-Income (DTI) Requirements
While the USDA program is highly flexible, lenders still need to verify your ability to repay.
- Credit Score: A minimum FICO credit score of 620 is generally required. If your score is 640 or higher, you qualify for automated approval through the USDA’s Guaranteed Underwriting System (GUS), which streamlines the process significantly. If your score is between 600 and 639, you may still qualify through manual underwriting, though this requires a closer look at compensating factors like rent history or substantial savings.
- Debt-to-Income (DTI) Ratio: The standard DTI ratio for a USDA loan is 29/41. This means your housing costs (mortgage, taxes, insurance) should not exceed 29% of your gross monthly income, and your total monthly debt payments (housing plus student loans, car payments, credit cards) should not exceed 41%. However, if you have a credit score above 640, these ratios can often be exceeded with automated underwriting approval.
If you are exploring your financing paths, you can review our comprehensive list of Mortgage Loan Options to see how these credit terms match up with other programs.
Property Eligibility and Maps for a USDA Loan Walton County FL
The most exciting aspect of buying in this region is that 99.2% of Walton County is eligible for a USDA home loan.
The USDA updates its property eligibility maps using U.S. Census Bureau population data. The major map revision in October 2023 remains the governing property eligibility standard across Florida through 2026.
Because USDA defines eligibility based on population density rather than whether an area “looks” rural, you can purchase homes in established suburban neighborhoods, not just remote farmlands.
- Eligible Cities: DeFuniak Springs, Freeport, and Paxton are entirely eligible.
- Exclusionary Zones: The only ineligible pockets in Walton County are highly dense coastal areas, such as portions of Miramar Beach and the immediate high-growth tourist corridors along Scenic Highway 30A.
Walton County USDA Loan Limits and Income Requirements for 2026
To keep the program focused on its target audience, the USDA enforces strict household income limits and maximum loan caps.
Income Limits for a USDA Loan Walton County FL
Unlike conventional loans where only the borrower’s income is analyzed, the USDA looks at the total combined income of everyone living in the household who is 18 or older—even if they aren’t on the mortgage.
For Walton County in 2026, the standard income limits are:
- 1 to 4 Person Household: $119,850
- 5+ Person Household: $158,250
Pro-Tip on Deductions: If your household gross income is slightly over the limit, don’t panic! The USDA allows deductions that can lower your qualifying “adjusted” income. Deductions include $480 per dependent child, childcare expenses for children under 12, and medical expenses for elderly or disabled household members.
2026 Loan Limits for Walton County
In 2026, the USDA loan limit for Walton County is $433,020 for a 1-unit property. This is a decrease from the $483,000 limit in 2024 and 2025, reflecting shifts in market data.
To put this in perspective, the average USDA loan value in Walton County was $247,500 across the loans originated in 2024. With an average loan-to-value (LTV) ratio of 99.2% (compared to just 69.1% for conventional loans), USDA buyers are successfully financing almost the entire purchase price of their homes.
Comparing USDA Loans vs. FHA, VA, and Conventional Mortgages
Choosing the right mortgage is all about comparing the upfront and long-term costs. Here is how the USDA loan Walton County FL program stacks up against other popular loan types in 2026:
| Feature | USDA Loan | FHA Loan | VA Loan | Conventional Loan |
|---|---|---|---|---|
| Minimum Down Payment | 0% | 3.5% | 0% | 3% |
| Minimum Credit Score | 620 | 580 | None (620 preferred) | 620 |
| Upfront Fees | 1.0% Guarantee Fee | 1.75% Upfront MIP | 1.25% to 3.3% Funding Fee | None |
| Monthly Mortgage Insurance | 0.35% (Low) | 0.55% (Higher) | None | Varies (removable at 20% equity) |
| Location Restrictions | Must be in eligible area | Anywhere | Anywhere | Anywhere |
| Income Restrictions | Yes (Household caps) | None | None | None (unless using special programs) |
For many buyers, the USDA option easily beats out an FHA loan. On a $300,000 purchase, the USDA’s lower upfront fee (1.0% vs FHA’s 1.75%) and lower monthly fee (0.35% vs FHA’s 0.55%) can save you roughly $50 a month and thousands over the life of the loan.
If you want to compare other low-down-payment paths, check out our guide on Low Down Payment Mortgage Chicago and nationwide options.
Step-by-Step Application Process for Walton County Buyers
Applying for a USDA loan does not have to be stressful. At Simply Financial Inc, we specialize in guiding you through a seamless, step-by-step process:
- Verify Your Household Income: Gather your last two years of tax returns, W-2s, and your most recent consecutive 30 days of paystubs. We will calculate your household adjusted income to ensure you are under the Walton County limits.
- Get Pre-Approved: We will review your credit history and calculate your DTI ratios. To get started, you can easily Pre-Qualify Chicago Mortgage Pre-Approval or connect with our Florida-licensed specialists.
- Find a USDA-Eligible Home: Partner with a real estate agent who knows Walton County well. Focus your search in Freeport, DeFuniak Springs, or Paxton.
- Negotiate Seller Concessions: The USDA allows the seller to pay up to 6% of the purchase price toward your closing costs. This means you can truly walk away from the closing table with zero out-of-pocket expenses!
- Underwriting and USDA Review: Once your offer is accepted, our team processes the loan. After our in-house underwriters sign off, the file is sent to the local USDA Rural Development office for final approval. This extra step typically adds 2 to 7 business days to the standard 30-to-45-day closing timeline.
Frequently Asked Questions about Walton County USDA Financing
Can I buy a manufactured home with a USDA loan in Walton County?
Yes, but the manufactured home must meet strict requirements. It must be a new unit (or an existing manufactured home already financed with a USDA loan), permanently affixed to an approved foundation, built after June 15, 1976, meet HUD federal construction safety standards, and be classified as real property.
What are the average interest rates and closing costs for USDA loans in Florida?
For Section 502 Direct Loans, the subsidized interest rate is 5.00% (effective May 1, 2026), which can be reduced to as low as 1.00% with payment assistance. For Guaranteed Loans, rates are highly competitive and track closely with conventional 30-year fixed rates, averaging around 6.24% in early 2026.
The average closing costs for a USDA loan in Florida are $6,319, though this can vary based on the home’s purchase price. These costs can be entirely covered by negotiating up to 6% in seller concessions.
How do I check if a specific Walton County address is USDA-eligible?
You can search any address directly on the official USDA Eligibility Site. Alternatively, you can contact the local USDA Rural Development Crestview Area Office, which directly serves Walton County applications.
Conclusion
If you want to buy a home in Walton County, Florida, without draining your savings account, a USDA loan is your golden ticket. With $0 down, flexible credit guidelines, and nearly the entire county eligible for financing, there is no reason to let the dream of homeownership pass you by.
At Simply Financial Inc, we believe the mortgage process should be exciting, not exhausting. We are here to provide you with the expert guidance, transparent communication, and stress-free experience you deserve.
Ready to see if you qualify? Explore our USDA Loan Chicago educational resources or contact our team today to start your Florida homebuying journey!